
Inflation vs Wage Growth 2026: Your Raise Is Disappearing—Here’s the Money Plan That Fights Back
You finally get a raise.
Your paycheck is bigger.
For a moment, it feels like progress.
Then you pay the mortgage or rent.
You buy groceries.
You fill the gas tank.
You renew insurance.
You take the family out for dinner.
And somehow, despite making more money, you do not feel richer.
For millions of workers, that feeling is not imaginary.
The latest inflation vs wage growth 2026 numbers help explain why.
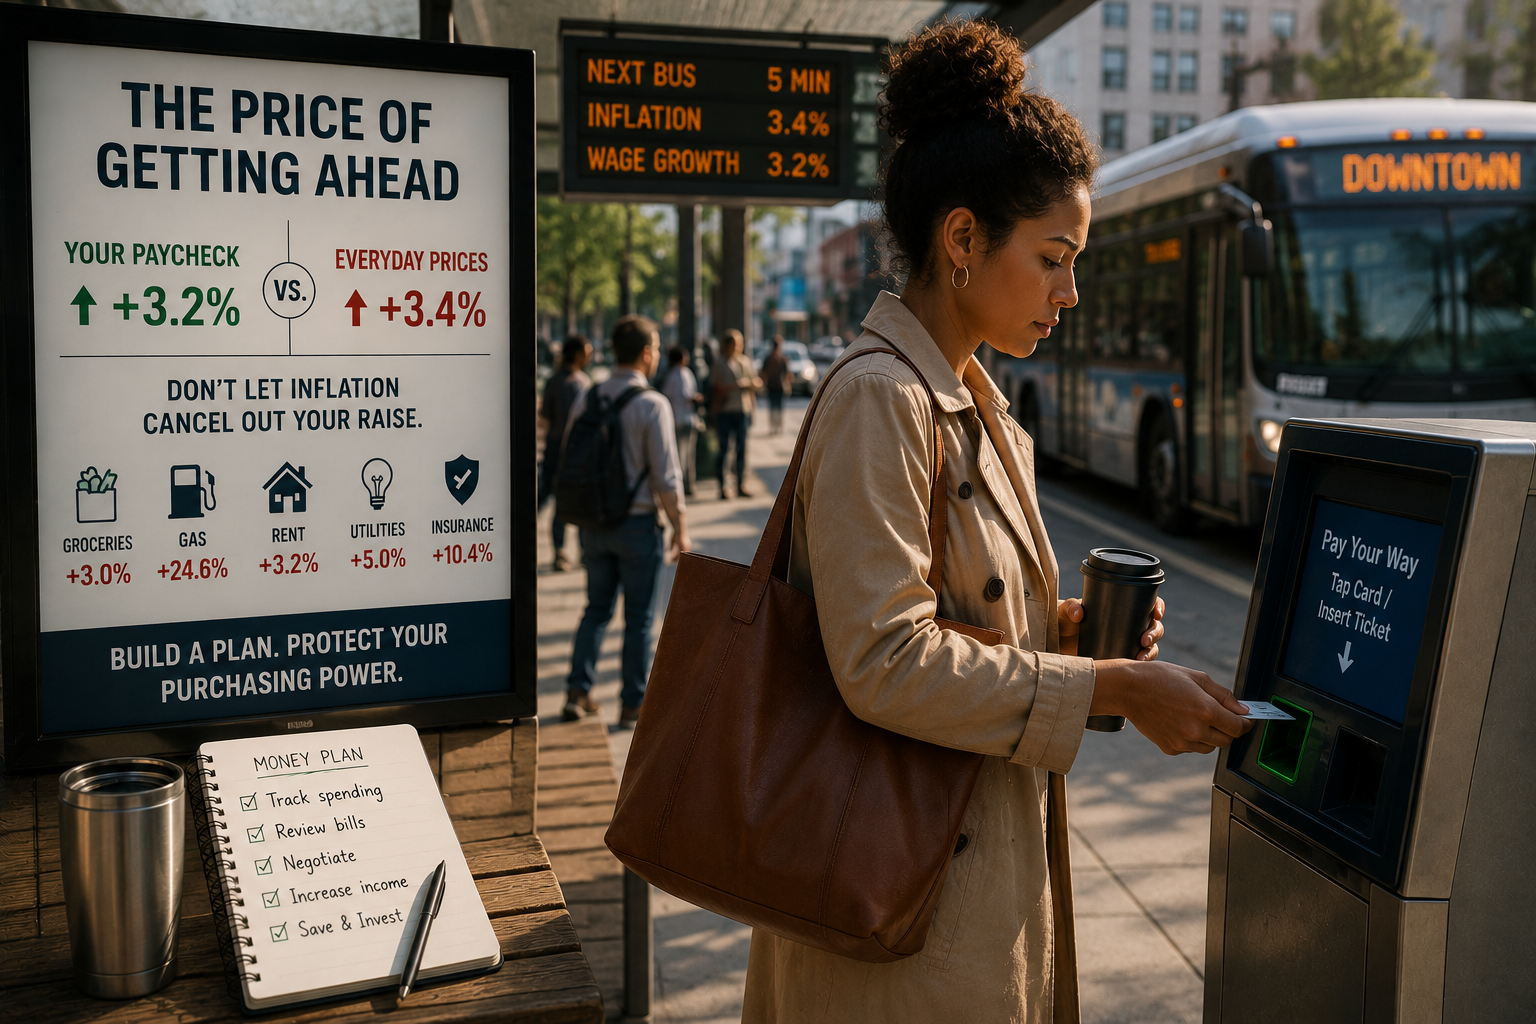
The U.S. Bureau of Labor Statistics reported that consumer prices were 3.4% higher in July 2026 than a year earlier. During roughly the same period, average hourly earnings for private-sector workers increased 3.2%.
That means the average worker’s paycheck grew in dollar terms, but prices grew slightly faster.
BLS’s inflation-adjusted earnings data makes the problem even clearer: real average hourly earnings were down 0.2% from July 2025 to July 2026. In other words, once inflation is considered, the average hourly worker had slightly less purchasing power than a year earlier.
That is why a 3% raise can feel like no raise at all.
And averages do not tell the whole story.
Your personal inflation rate may be much higher if a large share of your budget goes toward categories rising faster than the national average.
In July:
- Overall CPI was up 3.4% year over year.
- Food prices were up 3.0%.
- Food away from home was up 3.4%.
- Shelter costs were up 3.2%.
- Energy prices were up 14.7%.
- Airline fares were up 25.5%.
- Gasoline prices were up 24.6% from a year earlier.
So if you drive frequently, travel, rent in an expensive area or spend heavily on essential services, your household may feel much more pressure than the 3.4% headline number suggests.
This is where the inflation vs wage growth 2026 conversation becomes personal.
You cannot control the Consumer Price Index.
You cannot force your employer to give you a larger raise.
But you can control how much of your income growth survives after inflation.
This guide will show you:
- How to calculate whether your raise was actually a raise
- How to find your personal inflation rate
- Which household expenses deserve attention first
- How to negotiate recurring bills before cutting your lifestyle
- Why investing and saving still matter during inflation
- When changing jobs may be financially smarter than waiting for another raise
- How to build an “inflation gap” into your budget
- The 12-month money plan for protecting purchasing power
No panic.
No unrealistic advice telling you to stop buying coffee.
Just the math.
Inflation vs Wage Growth 2026: Why a Bigger Paycheck Can Still Buy Less
There are two ways to think about income.
Nominal income
This is the dollar amount you earn.
If your salary rises from $70,000 to $72,100, your nominal income increased 3%.
Real income
This measures what your income can actually buy after inflation.
Suppose prices rise 3.4% while your salary rises 3%.
Your paycheck is technically larger.
But your purchasing power has fallen slightly.
That is the difference between getting a raise and actually becoming better off.
Consider this example.
Previous salary:
$70,000
3% raise:
$2,100
New salary:
$72,100
That looks like progress.
But if the cost of maintaining the same lifestyle rises 3.4%, your previous $70,000 lifestyle would now cost approximately:
$70,000 × 1.034 = $72,380
You now earn:
$72,100
But your inflation-adjusted lifestyle costs:
$72,380
Difference:
-$280
You got a raise.
Yet you are approximately $280 behind in purchasing power.
That is the central problem behind inflation vs wage growth 2026.
What the Latest Numbers Are Really Saying
The July 2026 data deserves attention because wages and prices are moving almost neck-and-neck.
Average hourly earnings increased 3.2% over the year, while overall consumer prices rose 3.4%.
The gap is only 0.2 percentage point.
That may sound tiny.
But a small gap applied across an entire household budget can matter.
And the labor market is not booming strongly enough to make compensation growth feel guaranteed.
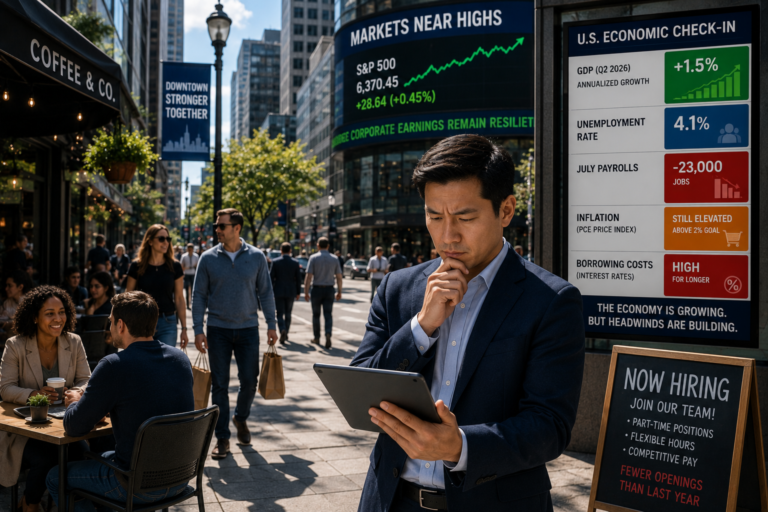
BLS reported that nonfarm payroll employment declined by 23,000 in July while unemployment was 4.1%. Average hourly earnings rose by only two cents during the month to $37.62.
That combination creates an uncomfortable environment:
- Prices are still rising.
- Wage growth is not clearly beating inflation.
- Hiring has softened.
- Workers may feel less confident demanding large raises.
- Household budgets remain under pressure.
This is why the solution cannot simply be:
“Ask for more money.”
Your plan needs several layers.
First, Calculate Your Personal Raise
Forget percentages for a moment.
Calculate what actually changed in your paycheck.
Suppose your salary increased from:
$60,000 to $63,000
That is a 5% raise.
But your gross salary does not tell you how much additional money you can spend.
After:
- Federal taxes
- State taxes
- Social Security and Medicare
- Retirement contributions
- Health insurance
- Other payroll deductions
your additional take-home income may be much smaller.
Imagine the $3,000 gross raise produces an additional:
$165 per month after deductions
That is approximately:
$1,980 per year
Now compare that $165 with the increases in your household expenses.
If rent increased $75 and auto insurance increased $40 monthly, those two bills alone consume:
$115
Your remaining raise:
$165 – $115 = $50
The raise did not disappear mysteriously.
Two recurring expenses absorbed 70% of it.
This is why the correct question is not:
“How big was my raise?”
Ask:
How much new monthly cash did my raise actually create after taxes and higher living costs?
Inflation vs Wage Growth 2026: Calculate Your Personal Inflation Rate
The national CPI measures a broad basket of consumer spending.
Your household has its own basket.
Someone who:
- Owns a paid-off home
- Drives little
- Rarely travels
- Has fixed insurance costs
may experience inflation very differently from someone who:
- Rents
- Commutes 60 miles daily
- Has children
- Travels frequently
- Pays large insurance premiums
Create a personal inflation audit.
Compare what you paid 12 months ago with what you pay today.
| Expense | Last Year | Today | Change |
|---|---|---|---|
| Housing | $2,000 | $2,080 | +$80 |
| Groceries | $800 | $840 | +$40 |
| Auto insurance | $220 | $245 | +$25 |
| Utilities | $300 | $320 | +$20 |
| Fuel | $250 | $320 | +$70 |
| Dining | $300 | $325 | +$25 |
| Total | $3,870 | $4,130 | +$260 |
Annualized increase:
$260 × 12 = $3,120
If your after-tax raise added only $2,400 annually, your household actually moved backward by:
$3,120 – $2,400 = $720
Alt text for table: Inflation vs wage growth 2026 household comparison showing how rising expenses can consume an employee’s raise.
This calculation tells you much more about your finances than national inflation alone.
The First Rule: Protect the Raise Before Lifestyle Inflation Takes It
There are two forces fighting for every raise you receive.
Economic inflation
Prices increase.
Lifestyle inflation
You voluntarily increase spending because you earn more.
The combination can destroy a raise quickly.
You receive $400 more monthly and think:
- Better car
- More dinners out
- New subscriptions
- More expensive vacation
- Upgraded apartment
- Higher shopping budget
Six months later, the extra money is gone.
The dangerous part is that when inflation rises afterward, your new lifestyle remains.
Use the 50/30/20 raise rule as a starting framework.
For every additional $100 of monthly take-home pay:
- $50 → wealth building
- $30 → inflation and rising living costs
- $20 → lifestyle improvement
If your financial situation is tight, change the percentages.
For example:
- $60 → debt/savings
- $30 → inflation
- $10 → lifestyle
The important principle is simple:
Do not allow 100% of a raise to become permanent new spending.
Find the Recurring Expenses Eating Your Raise
Inflation becomes dangerous when it enters recurring bills.
A $20 increase once is annoying.
A $20 increase every month costs:
$240 per year
Five recurring bills rising $20 each create:
$1,200 in additional annual spending
Start with the largest repeat expenses:
- Housing
- Insurance
- Transportation
- Phone/internet
- Utilities
- Subscription bundles
These deserve more attention than occasional small purchases.
Renegotiate Before You Cut
Many people immediately respond to inflation by cutting enjoyment.
They stop:
- Eating out
- Traveling
- Buying coffee
- Attending events
Sometimes cuts are necessary.
But first attack overpriced recurring expenses.
Auto insurance
Get several competing quotes.
Ask the current insurer about:
- Higher deductibles
- Mileage discounts
- Bundling
- Defensive-driving discounts
- Vehicle-safety discounts
Internet
Call the provider.
Ask:
- Which lower-cost plans are available?
- Are there retention offers?
- Are you paying for speed you do not use?
- Can equipment fees be removed?
Phone service
Review:
- Number of lines
- Device insurance
- Financing
- Premium data
- Streaming perks
Subscriptions
Use one rule:
Would I subscribe today at today’s price?
If no, cancel.
The goal is not deprivation.
It is reducing low-value fixed costs so inflation does not automatically control your paycheck.
The $100 Monthly Win Is Bigger Than It Looks
Suppose you reduce recurring costs by $100 monthly.
Annual savings:
$1,200
Over five years:
$6,000
If that $100 is invested monthly instead and earns an assumed 7% average annual return, the future value could be even larger.
That return is not guaranteed, but the point is important:
Recurring savings compound.
Negotiating one recurring bill can matter more than obsessing about isolated purchases.
Inflation vs Wage Growth 2026: Build an Inflation Gap
Your budget should include a deliberate gap between income and required spending.
Suppose take-home income is:
$6,000 monthly
Essential and planned spending:
$5,700
Gap:
$300
That is only 5% of income.
A few price increases can eliminate it.
Instead, work toward a 10%-plus gap where possible.
Example:
Take-home income:
$6,000
Total planned spending:
$5,250
Monthly gap:
$750
Now the household has room for:
- Inflation
- Repairs
- Saving
- Investing
- Unexpected expenses
Think of the gap as financial suspension.
A car without suspension feels every bump.
A budget with no margin feels every price increase.
Do Not Stop Investing Because Prices Are Rising
Inflation often creates the temptation to stop retirement contributions.
That can be a costly reaction.
If your budget is genuinely breaking, protecting essential cash flow comes first.
But whenever possible, continue:
- Employer retirement contributions
- Employer match eligibility
- Long-term investing
- Regular savings
Inflation reduces the purchasing power of cash over time.
Long-term investing is one of the tools households use to pursue growth above inflation, although investment returns are never guaranteed and markets can decline.
The mistake is using long-term investment money to solve every short-term price increase.
Before reducing retirement savings, look for:
- Unused subscriptions
- Expensive debt
- Overpriced insurance
- Lifestyle creep
- Excess cash sitting in low-yield accounts
- Spending categories that no longer provide value
Do not casually sacrifice 20 years of compounding to protect an expense you could negotiate today.
Use a Raise to Increase Retirement Contributions Automatically
Imagine your employer gives you a 4% raise.
Instead of allowing the entire increase into checking, raise your retirement contribution by one percentage point.
You still receive more take-home income.
Your future also receives a raise.
Example:
Salary:
$80,000
1% additional retirement contribution:
$800 annually
Monthly contribution increase:
Approximately $67
That may be easier psychologically than trying to find $67 later.
Use raises to increase savings before your lifestyle adjusts.
The Job-Switch Question
There comes a point where budgeting is not enough.
If your employer repeatedly gives raises below inflation while your market value is increasing, you may need to evaluate external opportunities.
Do not quit impulsively.
Research.
Compare:
- Base salary
- Bonus
- Retirement match
- Health insurance
- Commute
- Remote flexibility
- Paid leave
- Job stability
- Promotion path
A job paying $8,000 more may not be better if:
- Health insurance costs $4,000 more
- Commute costs $3,000 more
- Retirement match is worse
Calculate total compensation.
Still, changing employers has historically been one way some workers achieve larger pay jumps than relying only on annual internal raises.
Your loyalty should not require permanently losing purchasing power.
Build a Raise Conversation Around Value, Not Inflation
Walking into your manager’s office and saying:
“Inflation is 3.4%, so I need more money”
may not be persuasive enough.
Your employer does not necessarily determine compensation directly from CPI.
Build the case around value.
Document:
- Revenue created
- Costs reduced
- Customers retained
- Responsibilities added
- Productivity increased
- Skills gained
- Market compensation
Then say:
“My responsibilities and measurable contribution have increased significantly, and I would like to review whether my compensation accurately reflects the value and current market range of the role.”
Inflation supports your personal reason for asking.
Your business value supports the employer’s reason for saying yes.
Protect Yourself From the Credit-Card Inflation Trap
When prices rise faster than income, households often begin filling the difference with credit.
At first, it looks harmless.
Groceries are $40 higher.
Gas is $70 higher.
Insurance rises $50.
You put the difference on a card.
But the balance begins compounding.
Suppose your monthly shortfall is:
$300
After one year, before interest:
$3,600
That is not really a debt problem.
It started as a cash-flow problem.
Credit temporarily hid it.
If regular living expenses are repeatedly moving onto a credit card, stop focusing only on debt payoff.
Fix the underlying monthly shortfall.
Otherwise, you will pay the balance down and rebuild it again.
The Household Inflation Defense Table
| Problem | Weak response | Stronger response |
| Raise below inflation | Wait another year | Measure market value and prepare a compensation case |
| Insurance increase | Accept renewal | Compare carriers and coverage |
| Grocery inflation | Randomly cut food | Meal-plan around high-value staples |
| Rising fuel costs | Put gas on credit | Review commuting and transportation costs |
| Higher rent | Assume price is fixed | Negotiate or compare renewal alternatives |
| Subscription increases | Ignore small changes | Run quarterly recurring-cost audit |
| Shrinking savings rate | Stop investing entirely | Reduce low-value expenses first |
| Monthly shortfall | Use credit card | Restructure recurring expenses and income |
Inflation vs wage growth 2026 household defense table showing practical responses when prices rise faster than income.
Your 72-Hour Raise Audit
Whenever you receive a raise, bonus or promotion, do this before increasing spending.
Step 1: Calculate new take-home pay
Ignore gross income.
Use the amount actually reaching your bank account.
Step 2: Compare current expenses with last year’s expenses
Identify the inflation damage.
Step 3: Increase automatic savings
Do this before lifestyle spending expands.
Step 4: Attack one recurring bill
Use part of the raise as motivation to improve the budget further.
Step 5: Choose one lifestyle upgrade intentionally
You should enjoy financial progress.
Just do it consciously.
The 12-Month Inflation Defense Plan
Months 1–3: Measure
- Calculate personal inflation
- Compare wage growth
- Audit recurring expenses
- Identify the three fastest-growing costs
- Build a starter monthly margin
Months 4–6: Negotiate
- Compare insurance
- Review housing costs
- Reduce phone/internet expenses
- Cancel low-value subscriptions
- Prepare a compensation conversation if necessary
Months 7–9: Strengthen
- Increase emergency savings
- Increase retirement contributions after a raise
- Reduce expensive debt
- Improve career skills
Months 10–12: Reprice Your Life
Review:
- Income
- Expenses
- Savings rate
- Investment rate
- Career compensation
- Personal inflation
Then ask:
Am I financially stronger than 12 months ago?
Not:
“Did my salary increase?”
Those are different questions.
Inflation vs Wage Growth 2026: What Should Your Raise Actually Be?
There is no universal correct raise.
But use three benchmarks.
Inflation benchmark
Did compensation at least maintain purchasing power?
Market benchmark
Is your salary competitive for your:
- Occupation
- Experience
- Location
- Skills
Performance benchmark
Did your responsibilities or output increase?
A person who receives 4% while inflation is 3.4% technically gains a small amount of purchasing power.
But if their market value increased 10%, the raise may still be inadequate.
Inflation is only one benchmark.
Do Not Confuse Lower Inflation With Lower Prices
This is one of the biggest misunderstandings about inflation.
If inflation falls from 6% to 3%, prices generally are not going backward.
They are rising more slowly.
Suppose something costs:
$100
After 6% inflation:
$106
Then prices rise another 3%:
$109.18
Inflation declined.
The price still increased.
This explains why people can hear:
“Inflation is cooling”
while still feeling:
“Everything is expensive.”
Both can be true.
Households need income to catch up with the higher price level—not simply wait for the inflation rate to fall.
Build a Personal Cost-of-Living Index
Create your own simplified index with six categories:
- Housing
- Food
- Transportation
- Insurance
- Utilities
- Healthcare
Record the monthly amount every three months.
Example:
January total: $4,000
April: $4,060
July: $4,120
October: $4,170
Annual increase:
$170 monthly
Annualized:
$2,040
Now compare that with your annual after-tax raise.
This gives you a household-specific picture.
You do not need to argue about whether the national inflation number matches your life.
You will have your own number.
External Resource
For the official U.S. Consumer Price Index data used to measure changes in consumer prices, review the Bureau of Labor Statistics July 2026 CPI release:
https://www.bls.gov/news.release/archives/cpi_08122026.htm
The BLS reported that the CPI increased 3.4% over the 12 months ending July 2026, while food rose 3.0%, shelter 3.2%, and energy 14.7%.
Continue Building Your Financial Knowledge
Read more practical saving, income and wealth-building strategies on the True Wealth Moves blog:
https://truewealthmoves.com/wealth-blog
Use the True Wealth Moves resources page for financial tools, guides and calculators:
Final Verdict: Inflation vs Wage Growth 2026 Is Really About Purchasing Power
Your employer can give you a raise while your standard of living gets worse.
That is the lesson behind inflation vs wage growth 2026.
In July 2026, average hourly earnings were up about 3.2% from a year earlier while consumer prices were up 3.4%. BLS’s inflation-adjusted data showed real average hourly earnings down 0.2% over the year. The numbers are close.
But close is not the same as getting ahead.
And your household’s experience can be worse than the average when the expenses you use most are rising rapidly.
So stop measuring financial progress only by salary.
Measure:
- Take-home pay
- Personal inflation
- Monthly margin
- Savings rate
- Investment rate
- Debt
- Net worth
A raise is valuable only when some of it survives.
Your best defense is not predicting next month’s CPI.
It is building a household that has room to absorb inflation.
That means:
- Protecting part of every raise
- Auditing recurring bills
- Negotiating major expenses
- Avoiding lifestyle inflation
- Keeping credit cards from masking a monthly deficit
- Investing for long-term goals
- Growing your market value
- Being willing to change jobs when compensation repeatedly falls behind
You cannot control what the economy charges you.
But you can become much more intentional about what you accept, what you negotiate and what you keep.
That is the True Wealth Moves conclusion:
A raise is not measured by how much more money appears on your paycheck. It is measured by how much more life that paycheck can actually buy.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.




5 Comments