
Fed Rate Outlook 2026: Why the Next Move Could Still Be a Hike—and How to Protect Your Money Either Way
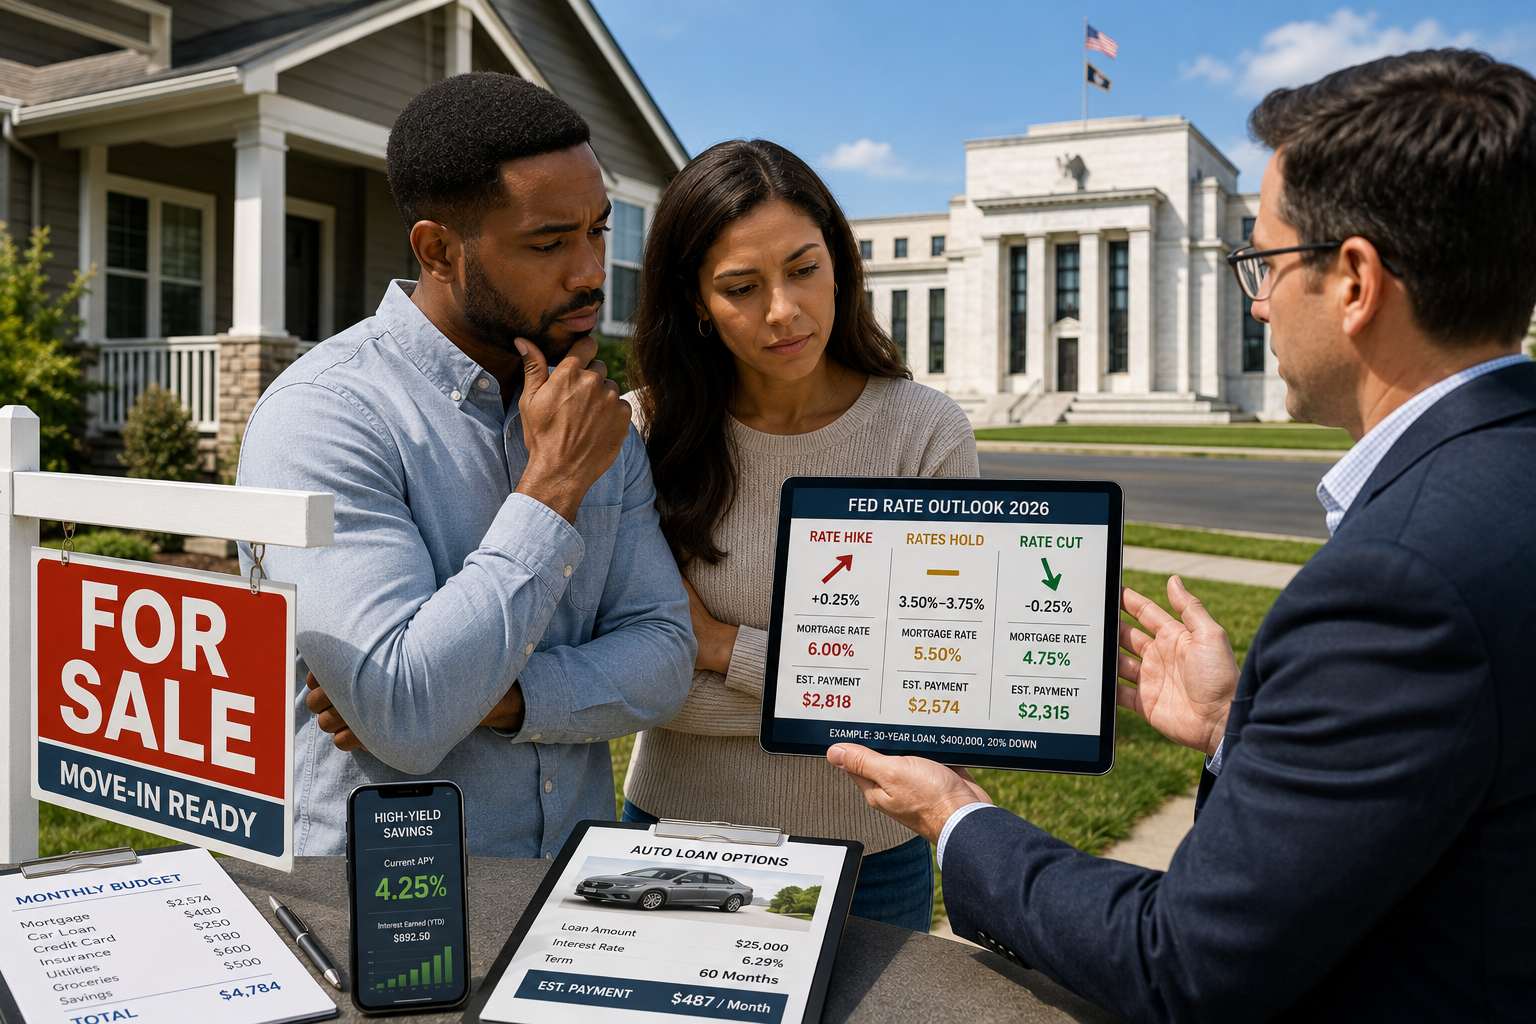
For much of the last few years, Americans became used to hearing the same prediction:
The Federal Reserve will eventually cut interest rates.
Mortgage borrowers waited.
Homebuyers waited.
Businesses waited.
Credit-card borrowers hoped relief was coming.
Investors tried to guess when cheaper money would return.
But the Fed rate outlook 2026 has become much more complicated.
The Federal Reserve held its benchmark federal funds target range at 3.50% to 3.75% on July 29, 2026, but the decision was not unanimous. Three Federal Open Market Committee members voted instead for a quarter-point rate increase.
That is important.
The debate inside the Fed is no longer simply:
“When will rates come down?”
Part of the debate is now:
“Are rates high enough to control inflation—or will they need to go higher again?”
At the same time, the latest inflation report gave policymakers a reason not to rush.
The Consumer Price Index rose only 0.1% in July, while the annual inflation rate eased slightly from 3.5% to 3.4%. Core inflation, which excludes food and energy, rose 0.2% for the month and 2.5% from a year earlier.
Financial markets interpreted the report as reducing the likelihood of an immediate September rate increase. Reuters reported that traders increasingly expected the Federal Reserve to hold rates steady at its next meeting, although markets still assigned a meaningful probability to a hike later in the year.
So households are facing an unusual situation.
Inflation is improving.
But inflation is still above the Fed’s 2% goal.
Employment has weakened somewhat.
But the economy has not collapsed.
Energy prices remain a risk.
And several Fed officials have publicly indicated that another rate increase remains possible if inflation fails to move sustainably toward 2%.
That means waiting for one specific Fed outcome could be a financial mistake.
The better strategy is building a household that can survive:
- A rate hike
- A long period of unchanged rates
- Or eventual rate cuts
This Fed rate outlook 2026 guide will show you exactly what each scenario could mean for:
- Credit cards
- Mortgages
- Homebuyers
- Auto loans
- High-yield savings accounts
- CDs
- Emergency savings
- Investing
- Refinancing
- Household cash flow
No pretending we can predict the Federal Reserve perfectly.
No telling you to restructure your entire financial life around one meeting.
Just a plan that works under multiple outcomes.
Fed Rate Outlook 2026: Where Interest Rates Stand Right Now
The Federal Reserve’s current target range for the federal funds rate is 3.50% to 3.75%.
The Federal Open Market Committee voted 9–3 on July 29 to leave the rate unchanged. The three dissenting officials preferred raising the range by 0.25 percentage point. citeturn404111search0
The Fed said economic activity continued expanding at a solid pace, but inflation remained elevated relative to its 2% goal and had been affected by supply shocks, including energy-price pressures related partly to conflict in the Middle East.
This tells us something important about the current Fed rate outlook 2026.
The Fed is not declaring victory.
It is waiting.
That matters because interest rates affect household finances through a long chain.
The federal funds rate does not directly determine your mortgage or credit-card APR.
But changes in monetary policy influence:
- Bank funding costs
- Prime rates
- Bond yields
- Mortgage rates
- Credit-card APRs
- Auto-loan pricing
- Savings yields
- Business borrowing
- Investment valuations
That means one Federal Reserve decision can eventually influence millions of household decisions.
Why the Fed Is Hesitating
The Federal Reserve has two major responsibilities:
- Maximum employment
- Price stability
Those goals can sometimes pull policy in opposite directions.
If inflation is too high, higher interest rates can reduce demand and help cool prices.
If employment becomes too weak, lower rates can support borrowing, investment and economic activity.
Right now, policymakers are receiving mixed signals.
Inflation is still above target
Annual CPI inflation was 3.4% in July.
That is lower than many previous peaks, but still above the Federal Reserve’s 2% long-term inflation goal.
Core inflation looks better
Core CPI increased 2.5% from a year earlier, suggesting that underlying inflation outside volatile food and energy categories has cooled more substantially.
Energy remains unpredictable
Although the energy index declined 1.5% during July, energy prices were still 14.7% higher than a year earlier.
That matters because an energy shock can affect:
- Transportation
- Shipping
- Airlines
- Manufacturing
- Food distribution
- Utilities
The labor market has weakened
Recent employment data has shown softer hiring conditions, which creates pressure on the Fed not to tighten unnecessarily. Reuters noted that weak labor-market data was one reason traders reduced expectations of an immediate September rate increase. The Fed is therefore balancing two risks:
Raise too much: damage employment and economic activity.
Do too little: allow inflation to remain above target or accelerate again.
That is why predicting the next move is difficult.
The Three Fed Scenarios Households Should Prepare For
Instead of betting your finances on one forecast, plan around three possibilities.
| Fed scenario | What could cause it | Likely household impact |
|---|---|---|
| Rates rise | Inflation reaccelerates, energy shock persists | More expensive variable-rate debt, stronger savings yields |
| Rates stay unchanged | Inflation cools gradually but remains above target | Borrowing stays expensive, savings yields remain attractive |
| Rates fall | Labor market weakens sharply or inflation cools faster | Borrowing costs may gradually decline, savings yields likely fall |
Fed rate outlook 2026 comparison showing household effects of rate hikes, unchanged rates and rate cuts.
The biggest mistake is preparing only for the third scenario.
Fed Rate Outlook 2026 Scenario One: The Fed Raises Rates Again
A rate hike would probably surprise many consumers who have spent years expecting eventual cuts.
But it remains possible.
Three Fed officials already favored a 25-basis-point increase at the July meeting.
Reuters’ survey of policymakers shows multiple officials continuing to express concern that inflation may require tighter policy if it does not return sustainably toward 2%.
What would another rate increase mean?
Credit-card APRs could rise
Many credit cards have variable rates connected to the prime rate.
If benchmark rates increase, variable APRs can increase relatively quickly.
Suppose you have:
$8,000 credit-card balance
APR:
22%
Approximate annual interest at that balance:
$8,000 × 22% = $1,760
If the APR rises to 23%:
$8,000 × 23% = $1,840
Difference:
$80 annually
One percentage point may not look dramatic.
But across multiple balances and years, higher rates matter.
More importantly, credit-card interest is already extremely expensive.
Do not wait for the Fed before attacking high-interest revolving debt.
The Credit-Card Rule
If you carry a balance:
- Stop adding unnecessary new charges.
- Protect minimum payments.
- Build a small emergency buffer.
- Target the highest APR aggressively.
- Consider a legitimate lower-cost balance-transfer or consolidation option when the full math works.
Do not delay debt payoff because you think the Federal Reserve may eventually lower rates.
Even after Fed cuts, credit-card APRs can remain very high.
Variable-Rate Debt Becomes More Dangerous
A rate increase could also affect:
- Home equity lines of credit
- Some private student loans
- Certain adjustable-rate mortgages
- Business credit lines
- Variable personal loans
Review every variable-rate debt you have.
Create a list:
| Debt | Balance | Current rate | Fixed or variable? |
| Credit card | $8,000 | 22% | Variable |
| HELOC | $30,000 | 8.5% | Variable |
| Auto loan | $24,000 | 6.2% | Fixed |
| Mortgage | $320,000 | 5.9% | Fixed |
Fed rate outlook 2026 debt audit showing fixed and variable household loans.
Fixed-rate debt is generally protected from future Fed increases.
Variable-rate debt is where you need to pay more attention.
Savers May Benefit From Higher Rates
Higher interest rates are painful for borrowers.
They can be attractive for savers.
If the Fed raises rates, yields on:
- High-yield savings accounts
- Money market deposit accounts
- Treasury bills
- CDs
may remain elevated or rise further, although individual bank rates do not move identically with Fed policy.
Suppose you have:
$30,000 emergency savings
At 3.5% APY:
Approximate annual interest:
$1,050
At 4.25%:
Approximate annual interest:
$1,275
Difference:
$225
This is why cash deserves attention when rates are elevated.
Do not leave a large emergency fund earning almost nothing in an account simply because that is where you have always banked.
Scenario Two: The Fed Holds Rates Higher for Longer
This may be the most important possibility.
A dramatic rate hike generates headlines.
A dramatic rate cut generates headlines.
But the most frustrating situation for consumers may simply be:
Nothing changes.
Rates stay elevated month after month.
This is currently plausible.
After July’s CPI report, markets increasingly expected the Fed to leave rates unchanged in September, while still recognizing that later action could depend on future inflation and employment data.
A prolonged hold affects household planning differently.
You should stop saying:
“I’ll do this when rates fall.”
That can delay important decisions for years.
Examples:
- Buying a necessary car
- Refinancing expensive debt
- Saving for a home
- Building emergency reserves
- Paying down a HELOC
If the decision works at today’s rates, evaluate it honestly.
If it only works after hypothetical future cuts, it may not be affordable yet.
Homebuyers: Buy the Payment, Not the Rate Forecast
A common phrase in real estate is:
“Marry the house, date the rate.”
The idea is that you can buy now and refinance later.
That may happen.
It also may not happen soon.
Refinancing costs money.
And future mortgage rates are not guaranteed.
A better rule:
Buy only when today’s payment works comfortably.
Suppose:
Purchase price:
$500,000
Down payment:
$100,000
Mortgage:
$400,000
Your affordability calculation should include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- HOA
- Maintenance
- Utilities
Do not say:
“The payment is too high now, but I’ll refinance next year.”
That is not a plan.
That is a prediction.
Fed Rate Outlook 2026 and Mortgage Rates
Mortgage rates do not track the federal funds rate one-for-one.
They are influenced heavily by longer-term Treasury yields, inflation expectations and bond-market conditions.
This means the Fed could cut rates and mortgage rates might not fall by the same amount.
Or mortgage rates could decline before the Fed officially cuts because bond markets anticipate future policy.
Homebuyers should therefore shop lenders rather than waiting for one Fed meeting.
Compare:
- APR
- Interest rate
- Points
- Origination fees
- Closing costs
- Rate-lock terms
- Lender credits
- Builder incentives
A 0.25 percentage-point difference can matter substantially over a long mortgage.
Existing Homeowners: Do Not Refinance Just Because Rates Move Slightly
Refinancing can make sense.
But the savings must recover the closing costs.
Use:
Break-even months = Refinance closing costs ÷ monthly payment savings
Example:
Closing costs:
$5,000
Monthly savings:
$200
Break-even period:
$5,000 ÷ $200 = 25 months
If you expect to remain in the home much longer than 25 months, the refinance may make sense.
If you expect to move next year, it may not.
Do not refinance merely because headlines say rates declined.
Do the math.
Auto Buyers Need a Payment-First Strategy Too
Auto loans can remain expensive when benchmark rates stay elevated.
The dealer may focus on:
- Monthly payment
- Promotional APR
- Trade-in allowance
- Cash rebate
You should focus on total cost.
Suppose one loan offers:
$40,000 financed at 7% for 72 months
Another allows you to buy a slightly cheaper vehicle:
$34,000 financed at 7%
The biggest saving does not come from predicting the Fed.
It comes from financing $6,000 less.
Your most powerful interest-rate strategy is often:
Borrow less.
Scenario Three: The Fed Eventually Cuts Rates
Rate cuts would likely receive enormous attention.
But a cut is not automatically good news.
Why is the Fed cutting?
There is a major difference between:
Good cut: Inflation is under control and the economy remains healthy.
and
Emergency cut: Hiring collapses, unemployment rises and the economy weakens sharply.
Lower rates may reduce borrowing costs.
But the reason behind them matters for:
- Jobs
- Stocks
- Business conditions
- Household income
Do not celebrate lower rates while ignoring the possibility that economic weakness caused them.
If Rates Fall, What Happens to Savings?
Savers need to understand this now.
Higher-yield savings accounts are attractive partly because rates are elevated.
If the Fed cuts rates substantially, banks may lower:
- Savings APYs
- Money-market yields
- New CD rates
That means today’s high cash yields should not be confused with permanent investment returns.
Do not keep long-term retirement money entirely in cash because the savings rate currently looks attractive.
Cash serves:
- Emergency savings
- Short-term goals
- Near-term purchases
Long-term investing serves a different purpose.
Should You Lock a CD Before Rates Fall?
Possibly.
If you have money you will not need during the CD term, locking a rate can make sense.
But review:
- Term
- APY
- Early withdrawal penalty
- FDIC or NCUA insurance
- Your liquidity needs
Do not lock emergency money that you may need next month.
A CD ladder may help some savers balance access and yield.
Example:
Instead of putting $20,000 into one 12-month CD:
- $5,000 → 3-month
- $5,000 → 6-month
- $5,000 → 9-month
- $5,000 → 12-month
As each matures, you can decide whether to:
- Spend
- Save
- Reinvest
Flexibility matters when rate expectations are uncertain.
Fed Rate Outlook 2026: What Investors Should Do
Investors often make the mistake of trying to trade every Fed decision.
They hear:
“Rates might fall.”
Buy stocks.
Then:
“Inflation is hot.”
Sell stocks.
Then:
“Fed may pause.”
Buy again.
This creates emotional investing.
Long-term investors should focus more on:
- Diversification
- Time horizon
- Asset allocation
- Fees
- Contribution consistency
- Risk tolerance
Interest-rate expectations are already reflected in market prices to some degree.
By the time you see a headline, professional investors have likely been trading the scenario for weeks or months.
Do not rebuild your entire retirement portfolio because of one CPI report.
Bonds May Behave Differently From Cash
When market interest rates decline, existing bonds with higher coupons can become more valuable.
When rates rise, existing bond prices can fall.
This is one reason bonds may play a different role from savings accounts.
However, bond funds can fluctuate.
A savings account is designed primarily for stability and liquidity.
Do not treat every fixed-income product as interchangeable.
Understand:
- Duration
- Credit risk
- Interest-rate risk
- Maturity
- Liquidity
before buying.
The Household Rate Defense Plan
Here is the TWM system.
Priority 1: Eliminate toxic variable debt
Especially high-interest credit cards.
Priority 2: Keep emergency cash productive
Use an appropriate insured high-yield account when available.
Priority 3: Do not make affordability depend on future cuts
Housing and cars must work at today’s payment.
Priority 4: Shop lenders aggressively
Rates vary between lenders even during the same Fed environment.
Priority 5: Preserve long-term investing
Do not turn retirement planning into Fed speculation.
Fed Rate Outlook 2026 Household Action Table
| Financial area | If rates rise | If rates stay | If rates fall |
| Credit cards | APR may increase | Remains expensive | Could decline slowly |
| HELOCs | Payments may rise | Remain elevated | May become cheaper |
| Mortgages | New loans may stay costly | Affordability remains tight | Refinancing opportunities may improve |
| Auto loans | Financing expensive | Payment pressure continues | New financing may improve |
| Savings accounts | Yields may rise | Attractive yields continue | APYs likely decline |
| CDs | New rates could improve | Good lock-in options remain | Existing locked rates become attractive |
| Stocks | Volatility possible | Earnings matter | Depends on reason for cuts |
| Bonds | Prices may face pressure | Mixed | Existing bonds may benefit |
Fed rate outlook 2026 household action table comparing credit, mortgages, savings and investments under hikes, holds and cuts.
The Rate-Hike Stress Test
Ask yourself:
If borrowing rates increase another 1 percentage point, what happens?
Credit cards
Can you still eliminate the balance?
HELOC
How much would the payment rise?
Future car
Could you afford the vehicle at a higher rate?
Home purchase
Would the payment still fit?
Business borrowing
Would the loan remain profitable?
This protects you from building a financial plan that works only under perfect conditions.
The Rate-Cut Stress Test
Now ask:
If savings rates fall by 1.5 percentage points, what happens?
Are you depending on interest income?
Have you confused cash yields with long-term portfolio returns?
Would you need to change your short-term savings strategy?
You should understand both sides.
The 90-Day Fed-Proof Money Plan
Days 1–30: Audit debt
List:
- Balance
- APR
- Fixed vs variable
- Minimum payment
Prioritize dangerous rates.
Days 31–60: Optimize cash
Review:
- Emergency savings
- Savings APY
- Bank fees
- Short-term goals
Move idle cash when appropriate.
Days 61–90: Stress-test major purchases
Before buying a:
- Home
- Car
- Business asset
calculate the payment at:
- Today’s rate
- 1 percentage point higher
- A realistic lower rate
If only the optimistic case works, wait.
When Should You Refinance?
Do not use a magical rule like:
“Always refinance after a 1% rate drop.”
Instead calculate:
- New payment
- New loan term
- Closing costs
- Break-even period
- Total interest
- How long you will keep the loan
Also avoid resetting a nearly completed loan unnecessarily.
A lower monthly payment can sometimes increase total interest when the loan term is extended.
Do Not Let the Fed Control Your Life
You should understand Fed policy.
You should not organize your entire financial future around it.
You cannot control:
- Inflation
- Oil prices
- FOMC votes
- Bond markets
- Employment reports
You can control:
- Debt balances
- Savings
- Loan size
- Credit quality
- Spending
- Career income
- Investment discipline
Those are stronger financial levers.
External Resource
For the Federal Reserve’s official monetary-policy decision and current federal funds target range, review the July 29, 2026 FOMC statement:
https://www.federalreserve.gov/newsevents/pressreleases/monetary20260729a.htm
The Fed held its target range at 3.50% to 3.75%, while three committee members voted for a quarter-point increase.
Continue Building Your Financial Knowledge
Read more practical saving, debt and wealth-building strategies on the True Wealth Moves blog:
https://truewealthmoves.com/wealth-blog
Use the True Wealth Moves resources page for financial tools, guides and calculators:
Final Verdict: Fed Rate Outlook 2026 Is About Preparing for More Than One Outcome
The biggest mistake households can make right now is assuming the next Federal Reserve move must be a cut.
It may be.
But the current Fed rate outlook 2026 remains uncertain.
The Fed held rates at 3.50% to 3.75% in July, but three policymakers wanted an increase.
July inflation then came in relatively mild, with CPI rising 0.1% during the month and 3.4% from a year earlier. That reduced expectations of an immediate September hike, but inflation remains above the Fed’s target and future policy remains dependent on incoming data.
So prepare for all three possibilities.
If rates rise:
- Attack variable debt.
- Protect cash flow.
- Take advantage of better savings yields.
If rates stay elevated:
- Stop postponing necessary financial decisions solely because you expect cuts.
- Buy only what works at today’s payment.
- Keep reducing debt.
If rates fall:
- Evaluate refinancing carefully.
- Expect savings yields to decline.
- Understand why the Fed is cutting before assuming it is automatically good news.
The strongest household does not need to correctly predict Jerome Powell’s next move.
It can survive being wrong.
That is the True Wealth Moves conclusion:
Do not build your financial plan around where you think interest rates are going. Build it so you can win whether rates go up, stay high or finally come down.






One Comment