
Your First $10,000 System: The Wealth Blueprint That Helps Stuck People Finally Make Progress
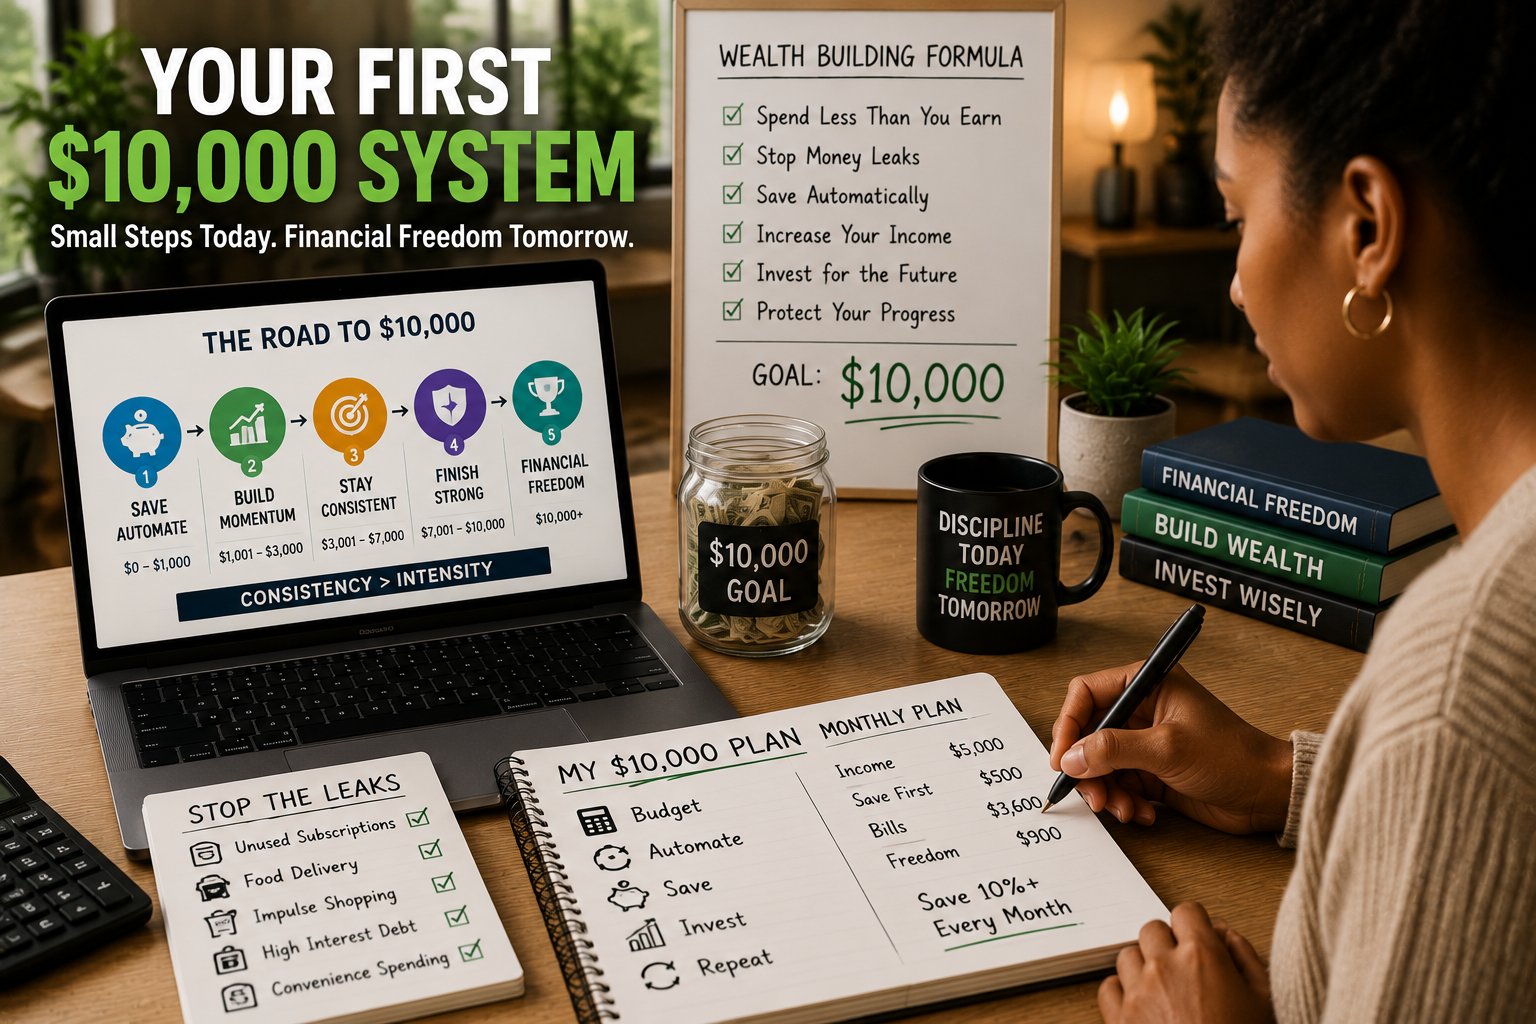
Most people think building wealth starts when they earn a high income.
They imagine someone making six figures, investing thousands every month, owning multiple properties, or having a successful business.
That image creates a problem.
It makes ordinary people believe wealth building is something they can start later.
After the raise.
After paying off debt.
After buying a house.
After earning more money.
After life becomes easier.
But wealth is usually not created by one dramatic financial moment.
It is created through systems.
The first major financial milestone for many people is not $100,000.
It is not becoming a millionaire.
It is reaching your first $10,000.
That first $10,000 changes everything because it proves something important:
You can create financial momentum.
A person with $10,000 saved has something more valuable than the money itself.
They have:
- A habit of saving
- A financial system
- Emergency protection
- More confidence
- More options
- Less dependence on every paycheck
- The ability to take advantage of opportunities
The challenge is that many people do not know how to get there.
They try random strategies:
- Cutting small expenses without a plan
- Opening investment accounts without emergency savings
- Saving whatever is left at the end of the month
- Following unrealistic budgeting advice
- Starting complicated financial systems they cannot maintain
The result?
They feel stuck.
That is why the first $10,000 system matters.
It is not about becoming rich overnight.
It is about building the financial foundation that makes bigger wealth goals possible.
This guide will show you:
- Why the first $10,000 is such an important milestone
- How to stop money leaks
- How to create your savings system
- How to increase your income strategically
- Where to keep your first $10,000
- How to automate progress
- What mistakes slow people down
- A realistic 12-month roadmap to reach the goal
No unrealistic promises.
No “skip coffee and become wealthy” advice.
Just a practical system.
First $10,000 System: Why This Milestone Matters
The first $10,000 is powerful because it changes your relationship with money.
Before reaching this milestone, many people operate in survival mode.
A financial emergency happens and they immediately think:
“How will I pay for this?”
A car repair.
A medical bill.
A job interruption.
A broken appliance.
A sudden move.
Without savings, every problem becomes a crisis.
After building your first $10,000, the same problems may still be frustrating.
But they become manageable.
The difference is not only financial.
It is psychological.
Money creates options.
A person with savings can:
- Negotiate at work
- Avoid high-interest debt
- Handle emergencies
- Invest during opportunities
- Make better decisions under pressure
The first $10,000 creates breathing room.
It is your first financial shield.
The First $10,000 Is Not One Goal
Many people make the mistake of thinking:
“I need $10,000 sitting in my bank account.”
That may be the final destination, but the journey should happen in stages.
A realistic structure:
| Milestone | Amount | Purpose |
|---|---|---|
| Starter emergency fund | $1,000 | Handle small surprises |
| Debt-control buffer | $2,500 | Prevent new credit-card dependence |
| Three-month foundation | $5,000 | Create stability |
| First $10,000 | $10,000 | Financial flexibility |
First $10,000 system showing savings milestones from starter emergency fund to financial flexibility.
Each milestone changes your financial behavior.
The first $1,000 proves you can save.
The next few thousand create stability.
The full $10,000 creates options.
Do not underestimate smaller wins.
They create the identity of someone who manages money well.
Step One: Stop the Financial Leaks
Before trying to save more money, find where money is already disappearing.
Most people do not have one massive financial problem.
They have dozens of small leaks.
Examples:
- Forgotten subscriptions
- Frequent food delivery
- Expensive insurance premiums
- High-interest debt
- Impulse shopping
- Unused memberships
- Convenience spending
- Overpriced phone plans
- Excessive bank fees
- Lifestyle inflation
A person may say:
“I cannot save $500 per month.”
But after reviewing their spending, they discover:
- $80 unused subscriptions
- $150 unnecessary food delivery
- $100 insurance savings opportunity
- $75 impulse purchases
- $95 random spending
Total:
$500 monthly opportunity
The money existed.
It simply lacked a system.
The Money Leak Audit
Complete a 30-day spending review.
Do not judge yourself.
Collect information.
Review:
Housing
Ask:
- Is my housing payment too high?
- Am I paying for space I do not use?
- Can I reduce utilities?
- Are there cheaper insurance options?
Transportation
Ask:
- Is my car payment limiting my progress?
- Is my insurance competitive?
- Am I spending too much on fuel?
- Are repairs predictable?
Food
Ask:
- How often do I order delivery?
- How much food is wasted?
- Are convenience purchases replacing planning?
Subscriptions
Ask:
- Do I use every service?
- Would I buy this again today?
Debt
Ask:
- Which balances have the highest interest?
- Are minimum payments keeping me stuck?
The First $10,000 System Expense Reset Table
| Category | Possible monthly savings |
| Cancel unused subscriptions | $25–$100 |
| Reduce food delivery | $100–$300 |
| Shop insurance rates | $25–$150 |
| Lower phone costs | $20–$75 |
| Reduce impulse spending | $50–$200 |
| Refinance expensive debt when appropriate | Depends |
| Sell unused items | One-time cash |
First $10,000 system expense reset showing common ways households can find savings.
The goal is not becoming miserable.
The goal is redirecting money toward something more valuable.
Step Two: Create a Separate Wealth Account
Many people fail because their savings has no separation.
Their paycheck arrives.
Bills leave.
Whatever remains sits in the same account.
Then unexpected spending happens.
The solution:
Create a dedicated savings account.
This account should have one purpose:
Building financial security.
A separate account creates psychological distance.
Money sitting beside your checking account feels available.
Money in a dedicated wealth account feels protected.
A good setup:
Checking account
For:
- Bills
- Daily spending
- Normal expenses
High-yield savings account
For:
- Emergency fund
- First $10,000 goal
- Short-term financial security
Investment accounts
For:
- Long-term wealth building
Do not mix every financial goal together.
Give every dollar a job.
Step Three: Automate the First $10,000 System
The biggest mistake people make:
“I will save whatever is left.”
Usually, nothing is left.
Successful savers reverse the order.
Income arrives.
Savings happens.
Then spending adjusts.
Example:
Monthly take-home income:
$5,000
Automatic savings:
$500
Remaining spending money:
$4,500
You do not need motivation every month.
The system creates progress automatically.
Automation removes decision fatigue.
Set up:
- Weekly transfers
- Payday transfers
- Automatic investment contributions
- Automatic debt payments
Your future self should not depend on your current self remembering.
How Much Should You Save Each Month?
There is no universal number.
Your amount depends on:
- Income
- Expenses
- Debt
- Family responsibilities
- Current savings
Here are examples.
| Monthly savings | Time to reach $10,000 |
| $250 | 40 months |
| $500 | 20 months |
| $750 | 14 months |
| $1,000 | 10 months |
| $1,500 | 7 months |
First $10,000 system timeline showing how monthly savings affects the time required to reach the goal.
The important point:
A slower plan is still a plan.
Someone saving $250 monthly is still building wealth.
Consistency matters more than intensity.
Step Four: Increase Income Instead of Only Cutting Expenses
Reducing expenses is important.
But there is a limit.
You cannot cut your way to unlimited wealth.
Income has more upside.
A person earning:
$50,000 annually
may improve finances by cutting $5,000.
But increasing income by:
$10,000
can create a larger long-term impact.
Ways to increase income:
- Ask for a raise
- Improve job skills
- Change employers
- Start a controlled side income
- Freelance
- Sell unused skills
- Learn valuable technology tools
- Build professional relationships
Your income is your largest wealth-building tool.
Protect it.
Improve it.
Do not ignore it.
The Income Boost Rule
When additional income arrives, do not immediately increase lifestyle spending.
Use a split system.
Example:
Extra monthly income:
$1,000
Allocation:
| Purpose | Amount |
| First $10,000 goal | $500 |
| Debt payoff/investing | $300 |
| Lifestyle improvement | $200 |
You improve today while strengthening tomorrow.
Step Five: Use Windfalls Strategically
Many people receive occasional money:
- Tax refunds
- Bonuses
- Gifts
- Overtime
- Commissions
- Side-income spikes
Instead of allowing windfalls to disappear, create a rule.
Example:
50% → Wealth goal
30% → Financial obligations
20% → Enjoyment
A tax refund does not need to become a shopping weekend.
A bonus does not need to become a luxury purchase.
Windfalls are opportunities to accelerate.
Where Should You Keep Your First $10,000?
The answer depends on the purpose.
If this money is emergency savings, safety matters more than maximum return.
Options may include:
High-yield savings account
Benefits:
- Easy access
- Low risk
- Interest earnings
Money market deposit account
Benefits:
- Potential competitive rates
- Liquidity
Treasury securities
Benefits:
- Government-backed options
- Potential tax advantages depending on circumstances
Investment accounts
Better for:
- Long-term money
- Retirement goals
Not ideal for emergency savings because markets can fall.
Imagine losing your job during a market downturn.
You need cash.
You do not want to sell investments after a major decline.
Match the account to the purpose.
Step Six: Protect Your Progress
Building $10,000 is difficult.
Keeping it requires discipline.
Common mistakes:
Using savings for lifestyle upgrades
A larger account balance does not mean you can immediately increase spending.
Investing emergency money
Emergency funds need stability.
Ignoring insurance
A single uninsured event can destroy years of savings.
Carrying high-interest debt
Credit-card interest can erase progress.
Stopping after reaching $10,000
The first milestone is the beginning.
Not the finish.
What Happens After $10,000?
Many people ask:
“What do I do after reaching the goal?”
The answer depends on your situation.
Possible next steps:
If you have high-interest debt
Attack the debt.
If you lack retirement savings
Increase retirement contributions.
If your emergency fund is complete
Start investing for long-term goals.
If income is unstable
Build more cash reserves.
If you want more freedom
Create additional income streams.
The first $10,000 gives you options.
Use those options strategically.
The Wealth Ladder After $10,000
| Milestone | Focus |
| $1,000 | Stop small emergencies becoming debt |
| $10,000 | Build financial stability |
| $25,000 | Strengthen emergency protection |
| $50,000 | Begin meaningful investing momentum |
| $100,000 | Experience stronger compound growth |
| $250,000+ | Wealth accumulation accelerates |
First $10,000 system wealth ladder showing financial milestones after initial savings.
The early years are often the hardest.
Later, money begins helping you create more money.
That is the power of investing and compounding.
The 12-Month First $10,000 Roadmap
Months 1–3: Foundation
Goals:
- Track spending
- Find money leaks
- Save first $1,000
- Create separate savings account
- Automate transfers
Months 4–6: Acceleration
Goals:
- Increase savings rate
- Reduce expensive debt
- Add income opportunities
- Reach $3,000–$5,000
Months 7–9: Momentum
Goals:
- Maintain consistency
- Increase income
- Save bonuses and extra money
- Reach $7,500+
Months 10–12: Completion
Goals:
- Reach $10,000
- Review financial system
- Create next wealth goal
- Begin investing strategy if appropriate
The exact timeline will vary.
The system matters more than the speed.
The Psychology of Your First $10,000
The biggest transformation is not the money.
It is your identity.
You move from:
“I always struggle with money.”
to:
“I know how to create financial progress.”
That confidence changes behavior.
You become someone who:
- Checks accounts regularly
- Makes intentional purchases
- Plans ahead
- Avoids unnecessary debt
- Invests consistently
- Thinks about opportunities
Money habits compound just like investments.
A person who learns to save $10,000 is more likely to save $50,000.
A person who learns to manage $50,000 is more likely to build $500,000.
The first milestone creates the foundation.
External Resource
The Consumer Financial Protection Bureau provides guidance on budgeting, saving strategies and building emergency savings habits:
https://www.consumerfinance.gov/consumer-tools/savings
Continue Building Your Financial Knowledge
Read more practical saving, investing and wealth-building strategies on the True Wealth Moves blog:
https://truewealthmoves.com/wealth-blog
Use the True Wealth Moves resources page for financial tools, guides and calculators:
Final Verdict: The First $10,000 Changes Everything
Building wealth does not begin when you become wealthy.
It begins when you create your first financial system.
The first $10,000 system teaches you the habits that create long-term success:
- Spend intentionally
- Save automatically
- Control money leaks
- Increase income
- Protect your progress
- Give every dollar a purpose
- Build financial confidence
Your first $10,000 will not solve every financial problem.
But it changes your position.
You move from reacting to life.
To preparing for it.
You move from hoping money improves.
To actively building improvement.
Remember:
The first $10,000 is not just a number.
It is proof that your financial future can be different from your financial past.
That is the True Wealth Moves conclusion:
Wealth is not built by one perfect decision. It is built by a repeatable system that turns small actions into lifelong progress.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.





