
Subscription Banking 2026: When Paid Bank Accounts Are Worth It—and When They’re a Money Leak
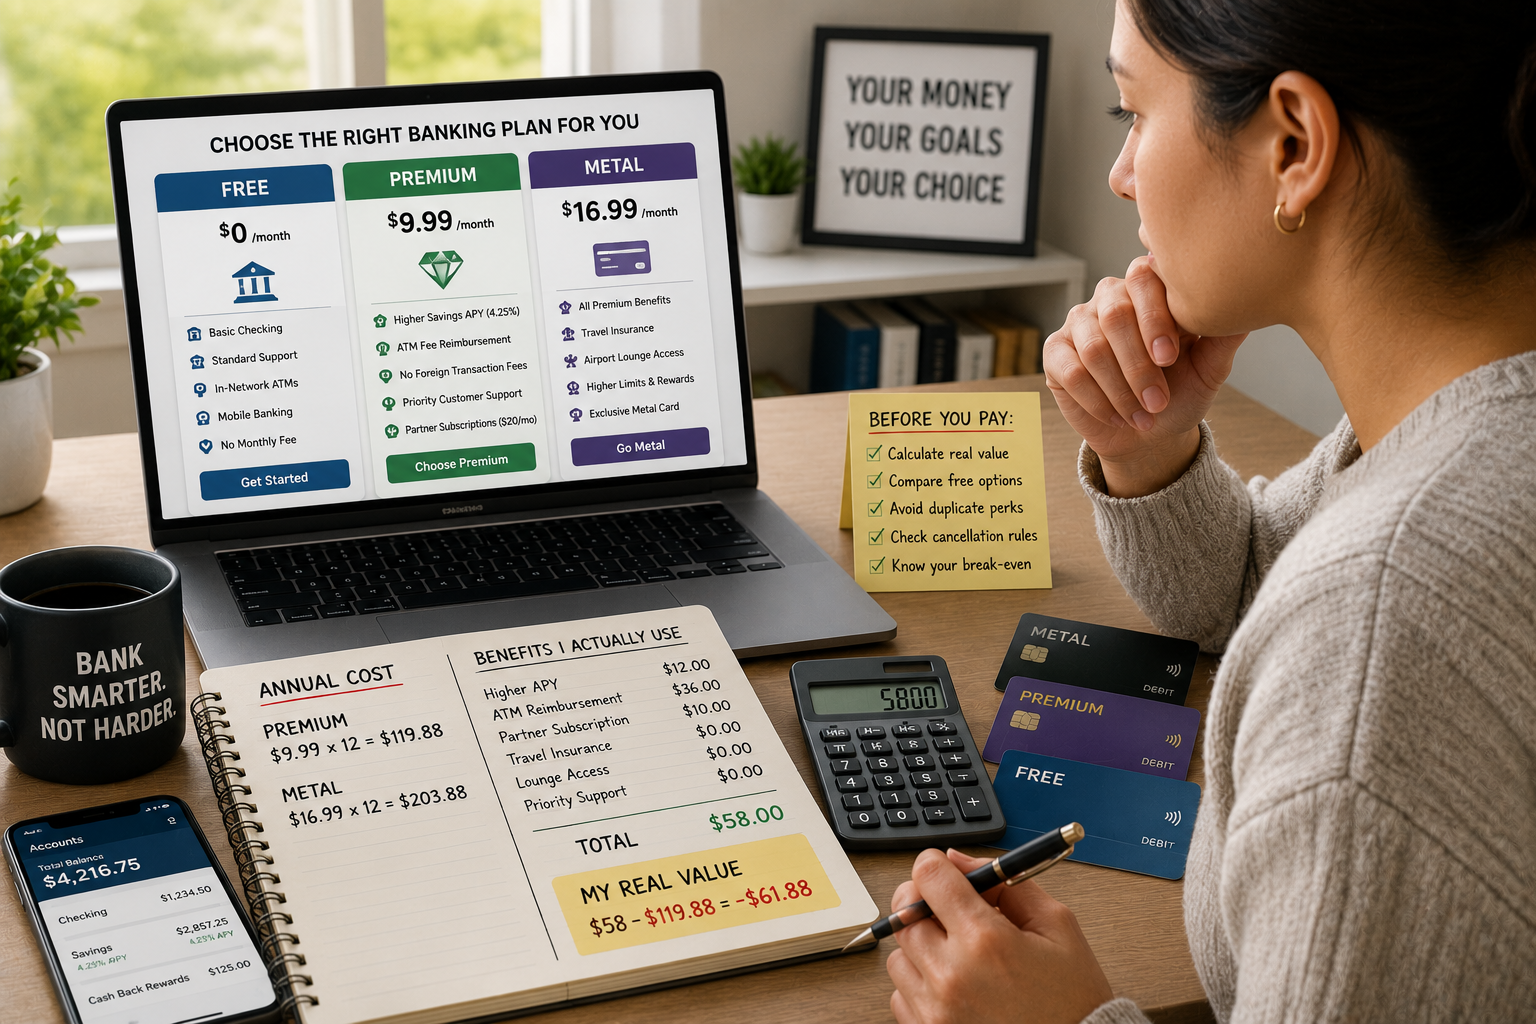
You probably already pay monthly subscriptions for entertainment, music, cloud storage, food delivery and software.
Now financial companies increasingly want banking added to that list.
Instead of offering only a basic checking account, some banks and financial apps are building tiered memberships that combine:
- Checking and savings features
- Higher savings rates
- Cashback rewards
- Travel insurance
- Airport-lounge access
- Lower foreign-exchange fees
- ATM reimbursements
- Priority customer support
- Credit-building tools
- Partner subscriptions
- Budgeting and investing features
The offer can sound powerful.
Pay $10 or $17 each month and receive benefits supposedly worth much more.
But subscription banking 2026 creates a familiar financial problem:
A bundle can look valuable even when you use only one small part of it.
You may pay for travel insurance when you rarely travel, airport-lounge access when you fly once a year, international transfers you never make, or higher savings rates on a balance too small to recover the monthly subscription fee.
The bank receives predictable recurring revenue.
You receive a collection of benefits that may or may not improve your financial life.
That does not mean every paid bank account is bad.
A subscription can be worth paying when the guaranteed savings exceed the fee and the benefits replace services you already buy.
It becomes a money leak when the account:
- Charges more than the benefits you actually use
- Encourages additional spending to earn rewards
- Requires a balance or direct deposit you cannot maintain
- Makes switching banks unnecessarily difficult
- Duplicates benefits from your credit cards or insurance
- Hides cancellation rules behind attractive monthly pricing
This guide will show you:
- How subscription banking works
- Why banks and fintech companies are embracing it
- How to calculate the true break-even point
- Which benefits deserve real value
- Which benefits are usually marketing noise
- How paid accounts compare with free checking
- How direct-deposit tiers differ from monthly subscriptions
- What to check before moving your paycheck
- When to cancel a paid banking membership
No loyalty to a banking app.
No assumption that premium means better.
Just the math.
Subscription Banking 2026: What Does It Actually Mean?
Subscription banking is a pricing model in which a bank or financial app charges a recurring monthly or annual fee for access to a package of financial features.
Instead of charging separately for each service, the company bundles several benefits into one membership.
A simplified example might look like this:
Free plan
- Basic checking
- Debit card
- Standard customer support
- Limited ATM benefits
- Standard savings rate
$10 monthly plan
- Higher savings rate
- Priority support
- Increased ATM allowances
- Reduced international-transfer fees
- Selected partner subscriptions
- Additional budgeting features
$17 monthly plan
- Premium card
- Travel insurance
- Higher ATM allowances
- Airport-lounge or travel benefits
- More partner subscriptions
- Better foreign-exchange limits
The model is familiar because it resembles streaming and software subscriptions.
But banking is different.
Your checking account holds:
- Your paycheck
- Your bill money
- Your emergency cash
- Your rent or mortgage payment
- Your financial history
- Your recurring transfers
That makes changing or canceling a banking subscription more complicated than canceling a television service.
The more services connected to one financial app, the harder leaving may feel.
That switching friction benefits the company.
Your job is to make sure the subscription benefits you more.
Why Banks Want Subscription Revenue
Banks and fintech companies traditionally make money through combinations of:
- Interest earned on deposits
- Lending
- Debit-card interchange
- Credit products
- Overdraft and account fees
- Investment services
- Partnerships
- Foreign-exchange fees
- Monthly maintenance charges
Subscription banking adds predictable recurring revenue.
If one million users pay $10 per month, that creates:
1,000,000 × $10 = $10 million per month
Annualized:
$10 million × 12 = $120 million per year
That revenue continues whether every customer fully uses the benefits or not.
This is the same reason gyms and streaming platforms love subscriptions.
Unused benefits can still generate revenue.
A company may advertise that a plan provides “up to $50 in monthly value.”
But it does not cost the company $50 to provide every benefit, especially when:
- Many customers never activate the benefits
- Partner services are discounted in bulk
- Insurance claims are infrequent
- Users maintain larger deposits
- Customers spend more through the app
- Benefits come with restrictions
The advertised value is not necessarily the provider’s cost.
More importantly, it is not necessarily your value.
The Subscription Banking 2026 Break-Even Formula
Use this formula before paying for any banking membership:
Monthly value of benefits you actually use − monthly subscription fee − added costs = net monthly value
Suppose a plan costs $9.99 monthly.
You receive:
- $4 in ATM fees avoided
- $3 in foreign-exchange savings
- $10 subscription to a service you already paid for
- $2 additional savings interest
- Priority support that you do not value financially
Your real monthly value is:
$4 + $3 + $10 + $2 = $19
Subtract the fee:
$19 − $9.99 = $9.01 net monthly value
That subscription may be worthwhile.
Now consider another customer with the same account.
They receive:
- $0 in ATM savings
- $0 in foreign-exchange savings
- $0 from the partner subscription because they do not use it
- $1 in additional savings interest
- Priority support they never contact
Real monthly value:
$1
Subtract the fee:
$1 − $9.99 = negative $8.99
Annual loss:
$8.99 × 12 = $107.88
Same plan.
Completely different result.
That is why you cannot judge a paid bank account from its benefits list alone.
Subscription Banking 2026 Comparison Table
| Benefit | Advertised appeal | When it has real value | When it is mostly noise |
|---|---|---|---|
| Higher savings APY | Earn more on cash | You keep a large enough balance to beat the fee | Your balance is small |
| ATM reimbursement | Avoid withdrawal fees | You regularly use out-of-network ATMs | You rarely withdraw cash |
| Travel insurance | Protection while traveling | You travel often and coverage fits your needs | You already have coverage |
| Foreign-exchange benefits | Lower international costs | You spend or transfer money abroad | Nearly all spending is domestic |
| Partner subscriptions | Services included in membership | They replace subscriptions you already pay for | You activate them only because they are included |
| Priority support | Faster help | You need frequent or complex assistance | You rarely contact support |
| Cashback rewards | Earn money on spending | Rewards apply to planned purchases | Rewards encourage more spending |
| Premium card | Metal or customized card | Almost no direct financial value | Appearance is the main attraction |
Subscription banking 2026 comparison showing when paid bank-account benefits provide real value and when they become subscription waste.
The Higher-Savings-Rate Trap
A paid plan may advertise a higher annual percentage yield on savings.
That can sound like an easy reason to upgrade.
But you must calculate how much additional interest the higher rate produces.
Suppose:
- Free account APY: 3.00%
- Paid account APY: 4.00%
- Monthly membership fee: $10
- Annual membership cost: $120
The paid plan gives you an additional 1 percentage point in interest.
If your average savings balance is $1,000, the approximate additional annual interest is:
$1,000 × 1% = $10
You pay $120 to earn approximately $10 more.
Estimated annual loss:
$120 − $10 = $110
Now suppose your average savings balance is $15,000.
Additional annual interest:
$15,000 × 1% = $150
Subtract the $120 annual fee:
$150 − $120 = $30 estimated net value
At that balance, the higher rate may cover the fee.
However, you should still compare the paid account with a free high-yield savings account.
You may be able to receive a competitive rate elsewhere without paying any subscription.
Use this break-even formula:
Required average balance = Annual subscription cost ÷ APY advantage
Example:
$120 ÷ 1% = $12,000
You need an average balance of approximately $12,000 just to recover a $120 annual fee from a 1-percentage-point APY advantage.
That calculation ignores taxes on interest.
The account might still provide other useful benefits, but the higher APY alone would not justify the subscription below that balance.
Free Checking Is the Real Competitor
The paid account should not be compared only with the company’s weaker free tier.
It should be compared with the best realistic alternative available to you.
Many banks, credit unions and financial apps offer accounts with:
- No monthly maintenance fee
- No minimum balance
- Early direct deposit
- Large ATM networks
- Competitive savings options
- Budgeting tools
- Mobile check deposit
- Fee-free transfers
The question is not:
“Is the premium plan better than the free plan inside this app?”
The better question is:
“Is this premium plan better than every suitable free account I can reasonably open?”
A company controls the comparison when it shows you only its own tiers.
You regain control by comparing the entire market.
Monthly Subscription vs Direct-Deposit Membership Tier
Not every premium banking tier charges a monthly subscription.
Some platforms unlock higher membership levels when you send a certain amount of qualifying direct deposit into the account.
For example, a company may offer:
- Basic membership without direct deposit
- Improved benefits after receiving a small qualifying deposit
- Premium status after receiving $3,000 or more in monthly deposits
This may appear free because there is no separate membership charge.
But direct-deposit requirements still have value to the company.
Moving your paycheck gives the platform:
- More deposits
- More transaction volume
- More debit-card spending
- Greater customer loyalty
- More opportunities to sell additional products
That arrangement can still benefit you.
But calculate the opportunity cost.
Ask:
- Will I lose a better APY at another institution?
- Will I lose a new-account bonus elsewhere?
- Does my employer allow split direct deposit?
- Can I maintain the required monthly amount?
- What happens if my income drops?
- Do benefits disappear immediately if I miss the threshold?
- Is premium status based on gross deposits or qualifying payroll deposits?
A direct-deposit tier is not automatically superior to a monthly subscription.
It simply charges you in a different currency:
Your banking relationship.
The Partner-Subscription Illusion
Paid banking plans may include access to:
- News publications
- Fitness memberships
- Security software
- travel applications
- Food-delivery perks
- Cloud storage
- Lifestyle services
The combined advertised value can look enormous.
A plan costing $17 monthly might claim included subscriptions worth $100 each month.
That sounds like an $83 monthly profit.
But only when you would have paid for those services independently.
Suppose the plan includes four services:
| Included service | Retail price | Would you buy it separately? | Your real value |
| News subscription | $25 | Yes | $25 |
| Fitness service | $30 | No | $0 |
| Security software | $15 | Already included elsewhere | $0 |
| Travel app | $20 | No | $0 |
| Total | $90 | $25 |
The company advertises $90 in value.
Your real value is $25.
If the bank subscription costs $17, you may still receive $8 in monthly value.
But that result is very different from believing you are receiving $73 in savings.
Alt text for table: Subscription banking 2026 example comparing advertised partner-subscription value with the value a customer actually uses.
Never count a benefit simply because it exists.
Count it only when it replaces money you were already spending.
The Travel-Benefit Trap
Premium banking tiers often target travelers.
Benefits may include:
- Travel insurance
- Lounge access
- International ATM allowances
- Foreign-exchange benefits
- Delayed-flight protection
- Purchase protection
- Emergency assistance
These benefits can be valuable for frequent international travelers.
They may be nearly worthless for someone who takes one domestic trip each year.
You should also compare them with benefits already available from:
- Your travel credit card
- Employer travel coverage
- Homeowners or renters insurance
- Health insurance
- Auto insurance
- Airline status
- Another paid membership
Duplicate protection does not double your claim payment automatically.
It may simply mean you paid for overlapping coverage.
Read travel-insurance terms carefully.
Check:
- Eligible trips
- Required payment method
- Covered reasons
- Claim limits
- Deductibles
- Preexisting-condition exclusions
- Trip-length limits
- Geographic restrictions
- Whether the account must remain active
Do not assign a premium value to insurance you have not reviewed.
Cashback Can Become a Spending Trigger
A banking subscription may offer cashback on eligible debit-card purchases.
Cashback sounds like automatic profit.
It is not.
Cashback is a rebate on spending.
Suppose the plan costs $10 monthly and offers 2% cashback.
To recover the $10 fee through cashback alone, you need:
$10 ÷ 2% = $500 in eligible monthly spending
Annual eligible spending:
$500 × 12 = $6,000
If you already spend $500 each month in qualifying categories, the reward may cover the fee.
If you spend extra to reach the threshold, you lose.
You also need to confirm:
- Which merchant categories qualify
- Whether rewards are capped
- Whether online purchases qualify
- Whether returns reverse cashback
- When rewards are paid
- Whether direct deposit is required
- Whether credit transactions earn more than debit transactions elsewhere
Never spend $100 unnecessarily to earn $2 back.
The rebate does not make the purchase responsible.
Priority Support: Valuable or Marketing?
Priority customer service is difficult to value.
For someone who:
- Travels frequently
- Moves large transfers
- Owns a business
- Has complex account needs
- Has experienced repeated support problems
faster service may be valuable.
For a customer who rarely contacts the institution, priority support has almost no financial value.
There is also a deeper question:
Why must you pay extra to receive reliable assistance with your own money?
Premium support may be convenient.
But basic account support should still be safe and functional.
Do not upgrade solely because the standard service is intentionally frustrating.
That can reward poor customer service rather than solve it.
The Cancellation and Downgrade Trap
The monthly price can make a banking subscription appear flexible.
But some paid plans may involve:
- Annual commitments
- Downgrade fees
- Charges for a premium physical card
- Benefit termination before the billing period ends
- Insurance cancellation
- Loss of a higher APY
- Reward forfeiture
- Waiting periods before rejoining
A plan can be billed monthly while still requiring a longer commitment.
That distinction matters.
Before subscribing, ask:
- Is this genuinely month-to-month?
- Is there a 12-month commitment?
- Is the annual plan refundable?
- Will I pay a fee to downgrade?
- Must I return or pay for the premium card?
- What happens to partner subscriptions?
- When does insurance coverage end?
- Will accumulated rewards remain?
- What happens to my account if I cancel the paid tier?
Take screenshots of the cancellation terms.
A subscription is easier to join than to untangle after your paycheck, savings and bills are connected.
Is Your Money Actually Held at a Bank?
Some financial apps are not themselves banks.
They may provide banking services through partner institutions.
That does not automatically make them unsafe.
But you should understand:
- Which institution legally holds the deposits
- Whether the partner is FDIC-insured
- How pass-through insurance works
- Whether all product balances qualify
- What happens if the fintech fails
- How to contact the partner bank
- Whether investments or cryptocurrency are insured
- Whether funds are held in pooled accounts
Do not assume every balance visible inside a financial application has identical protection.
Bank deposits, investments and crypto assets can have different risk structures.
Before moving your emergency fund, read the deposit agreement.
The stylish app interface is not the legal account structure.
Subscription Banking 2026: The Seven-Step Audit
Complete this audit before paying for any banking membership.
Step 1: Calculate the annual cost
Multiply the monthly fee by 12.
- $9.99 monthly = $119.88 annually
- $16.99 monthly = $203.88 annually
- $25 monthly = $300 annually
Annual numbers make the cost easier to understand.
Step 2: List only benefits you will actually use
Do not include possible future benefits.
Step 3: Assign a conservative dollar value
Use what the benefit replaces in your budget, not its advertised retail value.
Step 4: Remove duplicated benefits
Check your credit cards, insurance and other memberships.
Step 5: Calculate the break-even point
For cashback, savings interest, ATM fees and transfers, calculate the activity needed to recover the fee.
Step 6: Compare at least two free alternatives
Do not accept the company’s internal comparison as the entire market.
Step 7: Read cancellation and deposit-protection terms
Know how to leave and where your money is legally held.
Who May Benefit From a Paid Banking Plan?
A paid membership may make sense when:
- You regularly travel internationally
- You make frequent foreign-currency transactions
- You use out-of-network ATMs often
- The plan replaces subscriptions you already pay for
- Your savings balance is large enough to benefit from a higher APY
- You need and use premium insurance benefits
- Cashback on normal spending exceeds the monthly fee
- Business tools replace separate paid software
- You value priority support and use it frequently
The key phrase is already use.
The plan should reduce existing costs.
It should not create new habits to justify itself.
Who Should Probably Use a Free Account?
A free account may be better when:
- Your balance is small
- You rarely travel
- You use in-network ATMs
- You do not need international transfers
- You already receive travel benefits from a credit card
- You do not use the included subscriptions
- You are trying to reduce recurring expenses
- The premium plan requires more spending
- You can receive a competitive savings rate elsewhere
- You are unsure whether your income will meet direct-deposit requirements
Simple banking is not inferior banking.
A free account that safely handles paychecks and bills may be more valuable than a premium membership full of unused features.
External Resource
Review the Consumer Financial Protection Bureau’s guidance on monthly bank-account maintenance fees, disclosure requirements and ways to compare or avoid account charges:
Continue Building Your Financial Knowledge
Read more practical banking, saving and wealth-building strategies on the True Wealth Moves blog:
https://truewealthmoves.com/wealth-blog
Use the True Wealth Moves resources page for financial tools, guides and calculators:
Final Verdict: Is Subscription Banking 2026 Worth Paying For?
Subscription banking 2026 can provide real value.
A paid account may help you:
- Earn more interest
- Reduce foreign-exchange costs
- Recover ATM fees
- Replace existing subscriptions
- Receive useful travel protection
- Earn rewards on normal spending
- Access financial and business tools
- Get faster support
But the subscription works only when the benefits produce more reliable value than the fee.
The biggest mistakes are:
- Counting benefits you never use
- Valuing subscriptions at retail prices you would never pay
- Paying for a higher APY on a small balance
- Duplicating travel insurance and card perks
- Spending more to earn cashback
- Ignoring annual commitments
- Assuming a fintech app is legally the bank
- Forgetting the renewal or downgrade rules
- Comparing only the company’s paid and free tiers
- Keeping the plan because switching feels difficult
Use the correct order:
- Identify the banking services you genuinely need.
- Calculate what you currently pay for them.
- Compare free accounts.
- Value only benefits you will use.
- Subtract the subscription fee.
- Review deposit protection and cancellation terms.
- Upgrade only when the result remains positive.
Do not pay $120 per year to earn $20 in extra savings interest.
Do not pay for airport lounges when you rarely fly.
Do not call a partner subscription “savings” when you never wanted it.
Do not keep a premium plan because the metal debit card feels exclusive.
The right bank account should help you manage money.
It should not become another monthly bill you forgot to question.
That is the True Wealth Moves conclusion:
Pay for banking only when the bank can prove—through your real numbers—that the subscription pays you back.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.





