
Auto Insurance Audit: 9 Brutal (But Powerful) Ways to Cut Your Premium in 2026
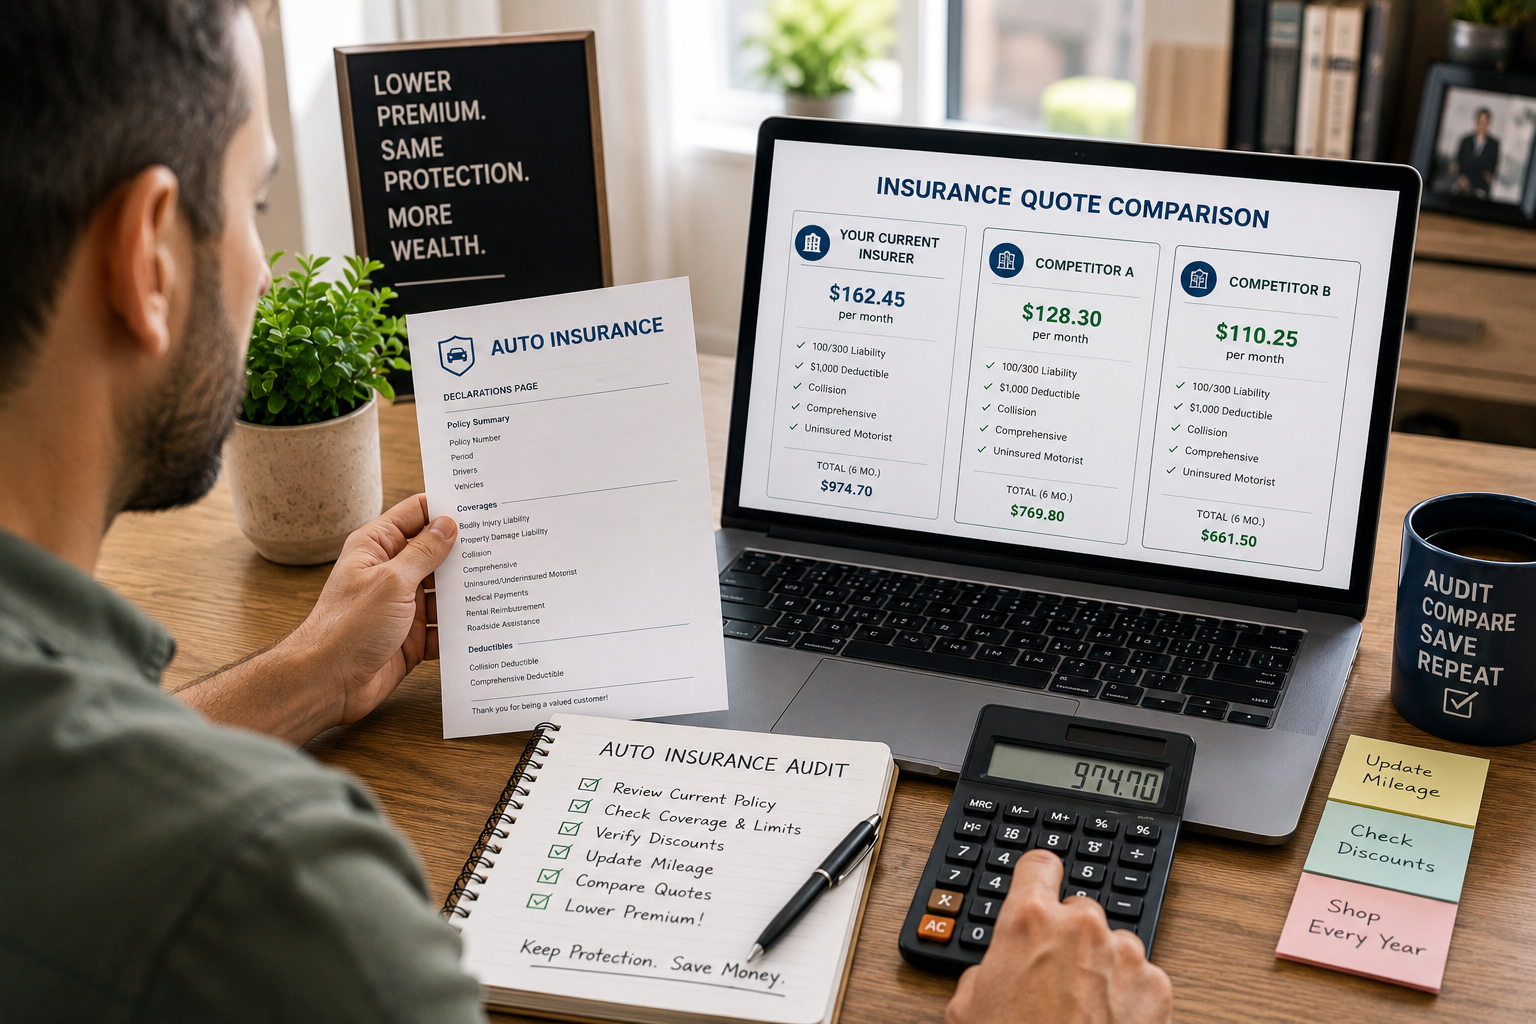
Auto insurance is one of the only bills that can go up even when you didn’t “do” anything.
No accident.
No ticket.
No new car.
No change in driving.
And yet the premium jumps like it’s trying to compete with your rent.
That’s why you need an auto insurance audit — not because you’re cheap, but because overpaying for insurance is one of the most common ways Americans leak money every single month.
This post is your True Wealth Moves system for doing an auto insurance audit the right way:
- why premiums feel out of control (without getting lost in insurance jargon)
- the hidden mistakes that keep people overpaying
- the exact checklist that can save you $30–$150+ per month
- and how to protect coverage while lowering cost (so you don’t “save money” and then regret it later)
No fluff. Just results.
Why auto insurance feels out of control in 2026
Auto insurance premiums aren’t just “a price.”
They’re an algorithm built from risk.
And in recent years, insurers have been repricing risk because the cost to repair and replace vehicles rose (parts, labor, electronics, supply chain delays). That means even safe drivers can see increases.
So the goal of an auto insurance audit is not to complain.
It’s to regain control by:
- removing what you don’t need
- optimizing what you do need
- and forcing insurers to compete for you again
Because loyalty is expensive in insurance.
The biggest mindset shift
Your insurance policy is not a “bill.”
It’s a contract.
And contracts can be renegotiated, restructured, or replaced.
An auto insurance audit is simply you reviewing that contract like a CEO reviewing expenses.
The 90-minute auto insurance audit checklist
Here’s the step-by-step that gets real savings without sacrificing safety.
Step 1: Get your current declarations page
Ask your insurer for your “declarations page” (or pull it from your portal).
This shows:
- coverages
- limits
- deductibles
- drivers
- vehicles
- discounts
- premium breakdown
You can’t do a real auto insurance audit from memory.
Step 2: Set your “coverage non-negotiables”
Before you shop, decide:
- What coverage must stay?
- What deductible can you truly afford if a claim happens?
A dangerous mistake is lowering coverage just to lower the premium.
A smart auto insurance audit lowers premium while keeping protection strong.
Step 3: Run the “deductible reality test”
A higher deductible can lower premium — but only if you can actually pay it.
Ask yourself:
“If I had to pay this deductible tomorrow, could I do it without debt?”
If the answer is no, don’t raise it.
Or raise it only to a level you can handle.
Step 4: Delete coverage that no longer makes sense
This is where people save money fast.
Common examples:
- Paying for rental reimbursement when you already have backup transportation
- Paying for roadside assistance when you already have it through your credit card or auto club
- Keeping full coverage on a very low-value vehicle when the math doesn’t justify it
This is the part of the auto insurance audit where you stop paying twice for the same protection.
Step 5: Fix your mileage and usage assumptions
If your insurer thinks you drive 15,000 miles per year but you drive 7,000, you might be overpaying.
Many people never update:
- commute distance
- work-from-home status
- mileage reductions
- vehicle use type
Your auto insurance audit should include a mileage check:
- current odometer
- estimated annual miles
- commute days per week
Step 6: Re-rate your policy (this is the secret move)
Sometimes the carrier you’re with has become expensive for your profile.
Not because you’re risky — because they’re repricing their book.
So the auto insurance audit requires a re-rate:
Get quotes from at least 3 sources:
- your current insurer (ask for a re-rate/review)
- a competitor carrier A
- a competitor carrier B
(optional: an independent agent who can quote multiple carriers)
This forces competition.
Step 7: Bundle strategically (but don’t get trapped)
Bundling home/renters + auto can reduce premiums.
But only if the bundled total is actually lower.
During your auto insurance audit, compare:
- auto alone
- renters/home alone
- bundle total
Don’t assume bundle equals cheaper.
Prove it.
Step 8: Turn on “real discounts” and ignore fake ones
Real discounts often include:
- safe driver programs (if they fit you)
- pay-in-full discount
- multi-policy discount
- defensive driving course (varies)
- good student (if applicable)
- low-mileage programs (if applicable)
But be careful with telematics tracking:
If you drive at night often, brake hard in city traffic, or have unusual patterns, tracking can sometimes raise rates or create stress.
A smart auto insurance audit tries discounts — but doesn’t surrender privacy blindly.
Step 9: Remove “policy clutter”
Policy clutter = things that create higher premiums unnecessarily:
- wrong address
- wrong garaging location
- outdated driver list
- old vehicle info
- old commute details
- duplicates across policies
Fixing these is boring — and it can save money.
The table: Auto insurance audit savings map
Auto insurance audit savings map showing the biggest premium drivers and the best actions to reduce cost safely
| Premium driver | What it looks like | Common mistake | Auto insurance audit fix |
|---|---|---|---|
| Deductible mismatch | low deductible with thin savings | raising deductible too high | set deductible you can actually pay |
| Mileage assumptions | insurer thinks you drive more | never updating mileage | update annual miles + usage |
| Coverage overlap | roadside/rental already covered elsewhere | paying twice | remove duplicate add-ons |
| Carrier mismatch | same insurer for years | loyalty tax | quote 3+ carriers every renewal |
| Bundle assumption | bundling without math | “bundle must be cheaper” | compare totals, not feelings |
| Discount neglect | discounts not applied | never asking | request discount review and proof |
The “right coverage” rule (don’t save in the wrong place)
An auto insurance audit is not about stripping coverage to the bone.
Here’s the True Wealth Moves rule:
Never reduce coverage below a level that would financially destroy you if something happens.
Instead, save money by:
- shopping
- removing duplicates
- correcting assumptions
- and optimizing deductibles and discounts
Your 30-day auto insurance audit action plan
If you want a simple schedule:
Week 1
- Pull declarations page
- Update mileage and garaging info
- Remove obvious duplicate add-ons
Week 2
- Request re-rate from current insurer
- Get 2 competitor quotes
Week 3
- Compare total annual cost + deductibles
- Choose the best-value policy (not just cheapest)
Week 4
- Set renewal calendar reminder
- Lock an insurance “savings buffer” so premium changes don’t shock you
The “premium shock” prevention trick
Once your auto insurance audit saves you money, do this:
Put 30–50% of the savings into a buffer fund.
That buffer protects you if premiums rise again next renewal.
Example:
You save $80/month → put $30–$40/month into “Insurance Buffer.”
Now future increases won’t wreck your month.
One evergreen external link
For a clear, consumer-friendly guide to understanding auto insurance coverages and terms, use this (and only this) external link in the post:
https://content.naic.org/consumer/auto-insurance
Two True Wealth Moves internal links
If you want more strategy posts like this:
https://truewealthmoves.com/wealth-blog/
If you want checklists and tools:
https://truewealthmoves.com/resources/
Final truth
Auto insurance can be out of control — but your response doesn’t have to be.
A real auto insurance audit can save serious money because it forces insurers to compete and removes hidden overpayments.
Do the audit.
Fix the assumptions.
Shop the contract.
Keep coverage smart.
Build a buffer with the savings.
That’s how you cut the premium without cutting your safety.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.





