Commercial Real Estate Refinancing 2026: Why High Rates Could Hit More Than Empty Office Buildings
When most people hear “commercial real estate crisis,” they picture an empty downtown office tower.
Lights off.
Floors vacant.
Workers staying home.
A landlord losing money.
It sounds like a problem for:
- Billionaire property owners
- Banks
- Commercial landlords
- Wall Street investors
But commercial real estate refinancing 2026 could matter to ordinary households much more than many people realize.
Why?
Because commercial buildings are usually financed with debt.
And unlike the typical 30-year fixed-rate mortgage on a house, many commercial real estate loans must be refinanced after:
- Five years
- Seven years
- Ten years
That means property owners who borrowed when interest rates were extremely low may now be forced to replace those loans with much more expensive financing.
At the same time, some office buildings are worth less than they were when the original loans were issued.
That creates a dangerous combination:
Higher borrowing costs + lower property values + weaker rental income.
The result can affect more than landlords.
Stress in commercial real estate can eventually reach:
- Regional banks
- Small businesses
- Local jobs
- Pension funds
- REIT investors
- City tax revenue
- Neighborhood development
- Small-business lending
The Mortgage Bankers Association estimates that approximately $875 billion of commercial and multifamily mortgage debt is scheduled to mature in 2026.
That does not mean $875 billion will default.
Far from it.
Many properties are healthy.
Banks are still lending.
Commercial mortgage originations have been recovering.
Some sectors—including high-quality multifamily, industrial properties, data centers and strong retail locations—continue to attract capital.
But refinancing is where weak properties can finally be exposed.
A building may survive for years with an old 3.5% loan.
The real test comes when that loan matures and the new financing costs 6%, 7% or more.
That is why commercial real estate refinancing 2026 deserves attention even if you have never owned an office building in your life.
This guide will explain:
- What the commercial real estate refinancing wall actually means
- Why commercial loans are different from residential mortgages
- Why office buildings face the greatest pressure
- How higher interest rates can break a previously profitable property
- Why falling property values make refinancing harder
- How regional banks can become involved
- Why small-business lending can be affected
- How REIT investors should evaluate exposure
- Why not every commercial property sector is in trouble
- What ordinary investors should watch before assuming another financial crisis is coming
No panic.
No prediction that every office tower is going bankrupt.
Just the financial connections.
Commercial Real Estate Refinancing 2026: What Is the “Maturity Wall”?
Commercial real estate is often financed differently from a homeowner’s mortgage.
A homeowner may borrow:
$400,000
using a:
30-year fixed-rate mortgage
The interest rate may remain unchanged for three decades.
Commercial real estate frequently works differently.
A property owner may finance:
$20 million
with a loan that matures in:
5 years
Even if the loan is amortized over 25 or 30 years, the full remaining balance may become due after only five or ten years.
The owner then usually refinances.
This system works well when:
- Property values rise
- Rental income rises
- Credit remains available
- Interest rates remain manageable
But what happens when several of those conditions reverse?
That is the problem.
Hundreds of billions of dollars in older commercial loans are reaching maturity during an environment where borrowing costs remain much higher than during the ultra-low-rate years.
The owner may discover that the old financial model no longer works.
The Refinancing Shock in Simple Numbers
Imagine an office building with:
$20 million loan balance
Old interest rate:
3.5%
Approximate annual interest:
$700,000
Now the loan matures.
New financing is available at:
6.5%
Approximate annual interest:
$1.3 million
Increase:
$600,000 per year
The building did not get larger.
The tenants did not improve.
The property did not suddenly produce another $600,000.
The cost of the debt simply changed.
If the property previously generated only:
$1 million
of annual cash flow before debt costs, refinancing can completely change the economics.
That is what makes refinancing different from a normal interest-rate discussion.
The borrower is not deciding whether to take a new loan.
The old loan is ending.
Something has to happen.
Commercial Real Estate Refinancing 2026 and the Property Value Problem
Higher rates are only part of the challenge.
Property values matter too.
Commercial real estate is often valued partly based on the income it generates.
Suppose an office building was worth:
$40 million
when the original loan was issued.
Loan:
$26 million
Loan-to-value ratio:
65%
That may have looked reasonable.
Now imagine:
- Office demand falls
- Rents weaken
- Vacancies rise
- Investment buyers demand higher returns
New estimated building value:
$28 million
The same $26 million loan now represents:
93% of the property’s value
A new lender may refuse to refinance that much.
The lender may offer only:
$18 million
Now the owner must somehow produce:
$8 million
to repay the old $26 million loan.
Possible outcomes:
- Owner contributes new cash
- New investor contributes equity
- Existing lender extends the loan
- Debt is restructured
- Property is sold
- Lender takes a loss
- Borrower defaults
That is the real refinancing wall.
It is not simply:
“Interest rates are high.”
It is:
The new loan may be smaller than the old loan.
Why Office Buildings Are the Biggest Problem
Commercial real estate includes many different property types.
They do not all face the same conditions.
The office sector experienced a structural shock after remote and hybrid work became more common.
Companies discovered they could operate with:
- Smaller offices
- Fewer desks
- Flexible work schedules
Some employers have brought workers back.
But many companies still use less office space than before.
That has created higher vacancy in numerous downtown markets.
Less occupancy means:
- Lower rent
- Higher tenant incentives
- More money spent attracting tenants
- Lower property values
A building financed under assumptions from 2018 or 2019 may now operate under completely different conditions.
Trophy Office vs Commodity Office
Even within offices, the market is divided.
High-quality modern buildings may continue attracting tenants.
Companies trying to persuade employees to return to the office often want:
- New construction
- Strong amenities
- Good locations
- Modern technology
- Attractive communal areas
Older buildings may struggle.
Imagine two properties.
Building A
- New
- Great location
- Modern amenities
- Energy efficient
- 92% occupied
Building B
- 35 years old
- Needs renovation
- Limited amenities
- 55% occupied
Calling both:
“Office real estate”
hides a huge difference.
Investors should avoid treating an entire property category as identical.
Commercial Real Estate Sector Risk Table
| Property type | Current general condition | Major refinancing risk |
|---|---|---|
| Older office | High stress | Vacancy and falling values |
| Premium office | Mixed to healthier | High borrowing costs |
| Multifamily | Generally stronger | Rate resets and local oversupply |
| Industrial/logistics | Relatively strong | Valuation and economic slowdown |
| Data centers | Strong demand | Massive capital requirements |
| Retail | Highly location-dependent | Weak tenants and consumer slowdown |
| Hotels | Cyclical | Travel demand and high maturity exposure |
| Healthcare property | Mixed | Operator finances and borrowing costs |
Commercial real estate refinancing 2026 property risk comparison showing office multifamily industrial retail hotel and data center exposure.
The most important lesson:
Commercial real estate is not one market.
Multifamily Real Estate Has a Different Problem
Apartment buildings are often considered safer than offices because people still need housing.
That is true.
But multifamily properties can still face refinancing stress.
Imagine a building purchased when:
- Interest rates were low
- Rent growth was strong
- Property values were rising
The buyer may have financed aggressively.
Then:
- Interest rates rise
- New apartment supply enters the market
- Rent growth slows
The building may still be nearly full.
But refinancing can still become difficult.
This distinction matters.
A property does not need to be empty to experience financing trouble.
Debt Service Coverage Ratio
One of the most important commercial-property measurements is:
Debt Service Coverage Ratio — DSCR
The simplified calculation is:
Property income ÷ debt payments
Suppose a building generates:
$1.5 million
in annual net operating income.
Annual debt payments:
$1 million
DSCR:
1.5
That provides some cushion.
Now refinancing raises debt payments to:
$1.4 million
New DSCR:
Approximately:
1.07
A lender may become uncomfortable.
If property income falls even slightly, there may not be enough cash to comfortably service the loan.
That is why rates matter so much.
Debt Yield Can Become the Refinancing Gatekeeper
Lenders increasingly focus on another number:
Debt yield
Simplified:
Net operating income ÷ loan amount
Suppose property income is:
$1 million
Requested loan:
$15 million
Debt yield:
Approximately:
6.7%
If the lender wants:
9%
the property may qualify for only around:
$11.1 million
That creates a refinancing gap.
The borrower may need millions of dollars in fresh equity.
A property can therefore be:
- Current on payments
- Not technically delinquent
- Still unable to refinance
That is one reason maturity dates matter so much.
The “Maturity Default”
Most people think default means:
“The borrower stopped making monthly payments.”
Commercial property can experience another type of failure.
The borrower makes every payment.
Then the loan reaches maturity.
The remaining principal becomes due.
The borrower cannot refinance.
That can create what is sometimes called:
maturity default.
The property looked healthy until the deadline arrived.
This is why upcoming maturities deserve attention even when delinquency rates appear manageable.
Commercial Real Estate Refinancing 2026 and Regional Banks
This is where ordinary Americans should begin paying attention.
Banks hold significant commercial real estate exposure.
Large national banks have diversified loan books.
Many smaller regional and community banks have historically been important lenders for:
- Office buildings
- Apartments
- Retail centers
- Local commercial properties
Suppose a regional bank has:
$10 billion loan portfolio
with:
$3 billion
in commercial real estate loans.
If a large portion of those loans becomes stressed, the bank may respond by:
- Increasing loan-loss reserves
- Tightening underwriting
- Making fewer new loans
- Requiring more collateral
That matters even if you never borrow money for commercial property.
Why?
Because the bank may also lend to:
- Restaurants
- Contractors
- Manufacturers
- Local retailers
- Small businesses
Stress in one loan category can reduce appetite elsewhere.
Why CRE Problems Can Hurt Small Businesses
Imagine a community bank suffers large commercial-property losses.
Management becomes cautious.
A local business owner asks for:
$500,000 expansion loan
The bank responds:
- Higher interest rate
- Larger down payment
- More collateral
- Or denial
The restaurant or business postpones expansion.
That can mean:
- Fewer jobs
- Less equipment purchasing
- Less construction
This is how commercial property stress can move through the real economy.
The connection is indirect.
But it is real.
Commercial Real Estate Refinancing 2026 and Local Governments
Cities rely on commercial properties for tax revenue.
An office tower worth:
$100 million
may generate much more property-tax revenue than one valued at:
$60 million
If downtown property values fall significantly, local governments may eventually face weaker tax collections.
At the same time, vacant buildings can affect surrounding businesses.
Fewer office workers can mean less revenue for:
- Restaurants
- Coffee shops
- Dry cleaners
- Parking garages
- Transit systems
- Local retailers
A struggling commercial district can therefore create broader economic effects.
The Downtown Feedback Loop
The cycle can look like this:
Workers stop commuting.
Office occupancy falls.
Retail traffic declines.
Businesses close.
Neighborhood activity weakens.
Office demand becomes less attractive.
Property values decline.
City tax revenue weakens.
Public investment becomes harder.
This is one reason cities are exploring:
- Office-to-residential conversions
- Downtown redevelopment
- Zoning changes
But conversion is difficult.
Why You Cannot Simply Turn Every Office Into Apartments
It sounds obvious.
Empty offices.
Housing shortage.
Convert them.
But commercial buildings were not necessarily designed for residential living.
Challenges include:
- Deep floor plates
- Limited windows
- Plumbing
- Fire codes
- Elevator layout
- Zoning
- Construction cost
Imagine an office floor that is:
150 feet deep
Apartments need:
- Windows
- Bathrooms
- Kitchens
Reconfiguration can be extremely expensive.
Some buildings are excellent conversion candidates.
Others are financially impractical.
CMBS: The Wall Street Part of Commercial Property
Some commercial mortgages are packaged into securities called:
Commercial Mortgage-Backed Securities — CMBS
The concept is similar in broad structure to mortgage-backed securities.
Many commercial property loans are pooled.
Investors buy securities backed by the cash flows.
CMBS investors may include:
- Asset managers
- Bond funds
- Insurance companies
- Institutional investors
When properties become delinquent, CMBS performance can weaken.
Office-related CMBS has been one of the most stressed areas.
But CMBS is only one part of the commercial lending system.
Do not look at one delinquency rate and assume every U.S. commercial loan has the same problem.
Commercial Real Estate Refinancing 2026 Is Not 2008
Comparisons with the global financial crisis are inevitable.
But important differences exist.
The 2008 crisis was centered heavily on:
- Residential mortgages
- Household leverage
- Weak underwriting
- Securities spread throughout the banking system
The current commercial-property stress is more concentrated.
It is particularly visible in:
- Certain office markets
- Specific vintages of loans
- Certain banks
- Certain CMBS pools
That does not mean there is no risk.
It means the risk structure is different.
Avoid dramatic claims such as:
“Commercial real estate will cause another 2008.”
The evidence does not justify assuming that outcome automatically.
There Is Also Good News in CRE
This story needs balance.
Commercial lending activity has been improving.
MBA expects commercial mortgage originations to rise substantially in 2026.
Banks have also been re-entering parts of the market.
Why?
Because not every property is distressed.
Lenders still want attractive loans backed by:
- Strong properties
- Good borrowers
- Healthy cash flow
Capital does not disappear.
It becomes more selective.
That means commercial real estate may increasingly divide between:
high-quality assets that refinance
and
weak assets that cannot.
The “Extend and Pretend” Strategy
When a property cannot refinance, lenders do not always foreclose immediately.
They may extend the existing loan.
Why?
Foreclosure may force the bank to recognize a large loss.
Imagine:
Loan:
$30 million
Property currently worth:
$20 million
Foreclosing may crystallize:
$10 million loss
Instead, the lender may extend the loan and hope:
- Interest rates fall
- Leasing improves
- Property values recover
Critics call this:
extend and pretend.
But extensions are not automatically irrational.
Sometimes giving a healthy borrower more time produces a better outcome for everyone.
The question is whether the property has a realistic path to recovery.
Refinancing Options for a Property Owner
A stressed borrower may have several options.
Refinance normally
Best outcome.
Add equity
Owner contributes cash to reduce the loan.
Bring in a partner
New investor contributes capital.
Sell the property
Debt is repaid from sale proceeds.
Modify the loan
Lender changes:
- Rate
- Maturity
- Payment structure
Hand the property back
Worst-case outcome for many owners.
Each loan is different.
That is why a maturity wall does not mean a wall of automatic defaults.
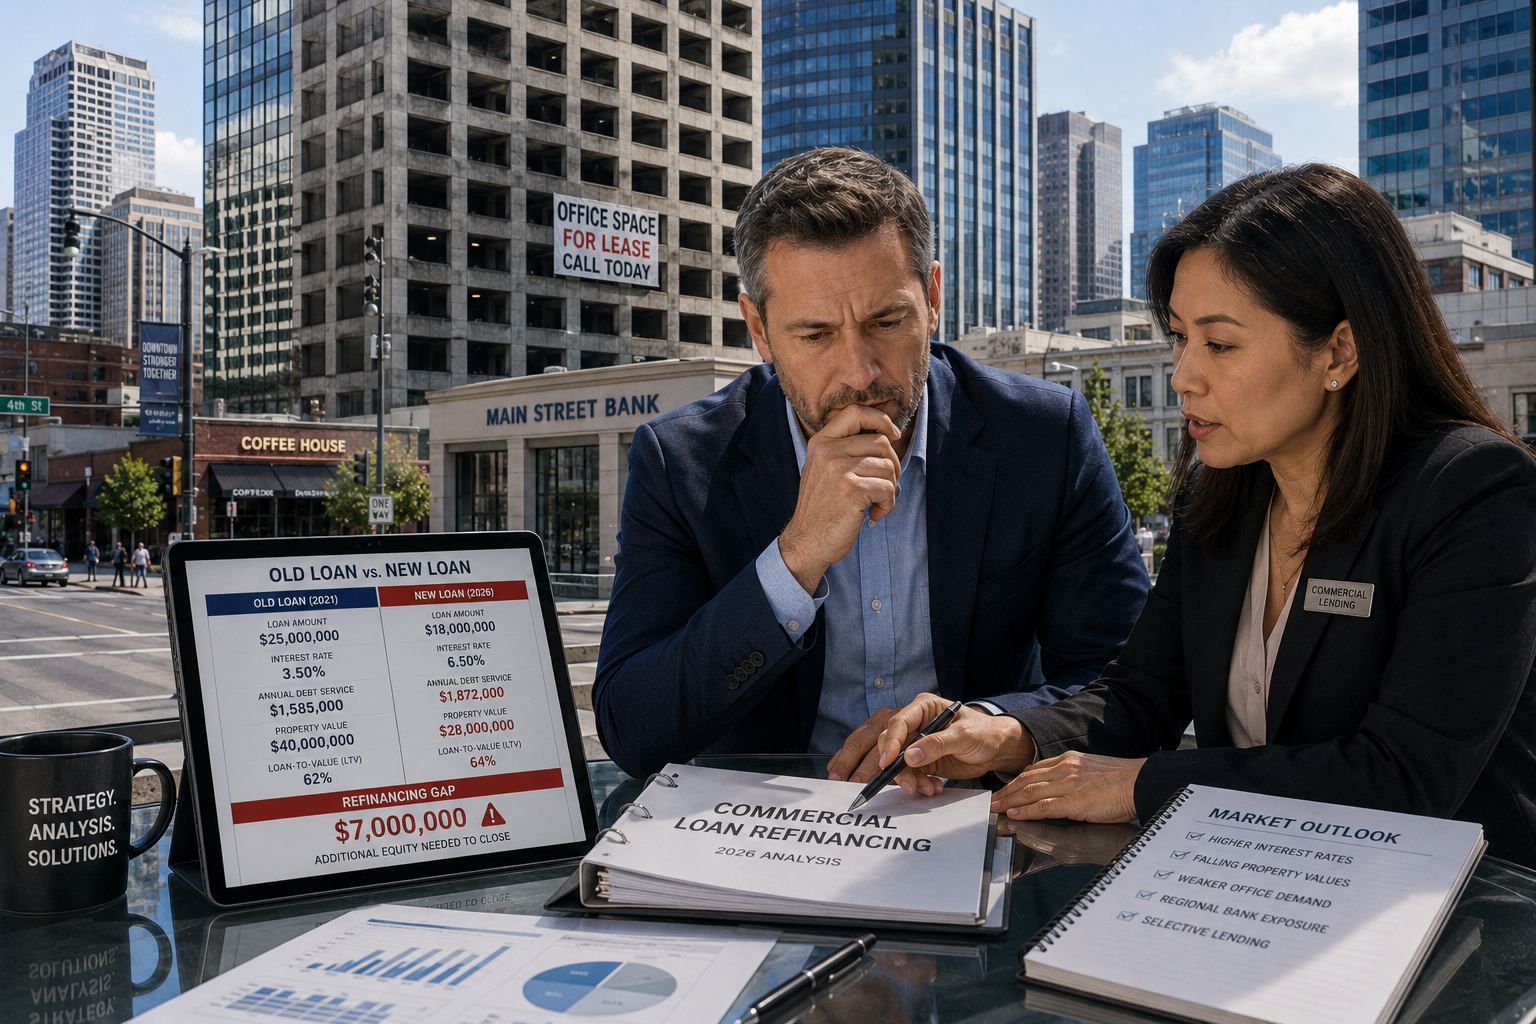
The Refinancing Gap Example
Old loan:
$25 million
New property value:
$30 million
New lender maximum LTV:
60%
Maximum new loan:
$18 million
Refinancing gap:
$7 million
The borrower must solve that $7 million gap.
Potential sources:
- Owner cash
- Preferred equity
- Mezzanine debt
- Property sale
- Lender restructuring
This is the number that can determine survival.
Commercial Real Estate Refinancing 2026 and REIT Investors
A REIT—real estate investment trust—allows investors to own interests in real estate businesses through publicly traded securities.
REITs may own:
- Apartments
- Offices
- Warehouses
- Data centers
- Cell towers
- Shopping centers
- Healthcare properties
Do not hear:
“Commercial real estate trouble”
and assume:
“All REITs are dangerous.”
A data-center REIT and an office REIT can have almost nothing in common operationally.
Analyze the actual portfolio.
The TWM REIT Risk Checklist
Before investing, check:
Property type
What does the REIT own?
Occupancy
Are buildings actually leased?
Tenant quality
Who pays the rent?
Debt maturity schedule
How much debt needs refinancing soon?
Interest rate
Is debt:
- Fixed
- Variable
Funds from operations
Is operating cash generation healthy?
Dividend coverage
Can the dividend be supported?
Property geography
Are assets concentrated in one weak market?
REIT Refinancing Risk Table
| Factor | Lower refinancing risk | Higher refinancing risk |
| Debt maturity | Spread over many years | Large amount due soon |
| Interest rate | Mostly fixed | Heavy variable-rate exposure |
| Occupancy | High | Falling |
| Property quality | Premium | Obsolete |
| Tenant base | Diversified | Concentrated |
| Cash flow | Stable | Declining |
| Balance sheet | Conservative | Highly leveraged |
Commercial real estate refinancing 2026 REIT checklist comparing lower and higher refinancing risk.
Do Not Buy a REIT Only Because the Dividend Is Huge
A struggling REIT may show:
10% dividend yield
That can look attractive.
But why is the yield 10%?
Sometimes because the stock price collapsed.
The market may expect:
- Dividend cut
- Asset sales
- Refinancing stress
A large dividend is not free money.
Check whether the underlying cash flow supports it.
Bank Stock Investors Should Check CRE Exposure
If you own individual bank stocks, review:
- Commercial real estate loans as percentage of total loans
- Office exposure
- Nonperforming loans
- Loan-loss reserves
Two banks can appear similar but carry very different commercial property risk.
Regional banks deserve particular attention because CRE exposure may represent a larger percentage of total assets.
Do not assume every regional bank is weak.
Analyze the institution.
Your Broad Index Fund Probably Does Not Need a CRE Panic Sale
Many investors own:
- S&P 500 funds
- Total-market funds
Those portfolios already contain:
- Banks
- REITs
- Property-related companies
A commercial real estate downturn does not automatically mean you should sell diversified funds.
Diversification exists partly because individual sectors experience problems at different times.
A retirement portfolio should not be rebuilt every time one industry enters a difficult cycle.
The Commercial Property Stress Transmission Table
| CRE problem | First impact | Possible household impact |
| Office values fall | Owner/lender losses | Reduced local investment |
| Loan cannot refinance | Bank restructuring/default | Bank becomes more cautious |
| Regional bank loses money | Tighter credit | Small-business loans harder to obtain |
| Downtown occupancy falls | Local businesses lose traffic | Jobs and city revenue pressured |
| REIT cash flow weakens | Dividend/stock pressure | Investor portfolio affected |
| Property taxes fall | City revenue weakens | Public budgets pressured |
Commercial real estate refinancing 2026 transmission table showing how property problems can reach banks businesses jobs and investors.
What Could Make the Problem Worse?
Several conditions could increase stress.
Rates stay high
Refinancing remains expensive.
Office demand weakens further
Property income falls.
Economy slows
Businesses reduce space.
Banks tighten lending
Refinancing becomes harder.
Property values decline again
Refinancing gaps become larger.
The worst scenario involves multiple pressures arriving simultaneously.
What Could Make the Problem Better?
There is also a path toward stabilization.
Rates decline
Debt becomes easier to refinance.
Office occupancy improves
Income rises.
Property values stabilize
Lenders gain confidence.
Banks recognize losses gradually
The system absorbs stress over time.
Buildings are repurposed
Some obsolete properties find new uses.
This is why commercial real estate stress may unfold over years rather than through one dramatic crash.
The Investor Warning Signs
Watch these:
Rising delinquency
Especially within a particular property category.
Falling occupancy
Income may weaken.
Large near-term debt maturities
Refinancing risk increases.
Variable-rate debt
Interest costs can change quickly.
Property-value write-downs
Collateral protection is shrinking.
Dividend cuts
Could signal cash-flow pressure.
One warning sign alone is not enough.
Look for combinations.
The TWM Commercial Real Estate Risk Test
Ask five questions.
1. What kind of property is it?
Office is different from apartments.
2. When does the debt mature?
Near-term maturities matter.
3. Can the property cover the new payment?
Run the refinancing math.
4. What is the property currently worth?
The old appraisal is irrelevant.
5. Who holds the loan?
Bank?
Insurance company?
CMBS investor?
Different lenders respond differently.
Should Ordinary Investors Avoid Commercial Real Estate Entirely?
No.
That would be an overreaction.
Commercial real estate still serves essential economic functions.
People need:
- Warehouses
- Apartments
- Hospitals
- Stores
- Data centers
- Hotels
The challenge is recognizing that:
property type + location + debt structure
matter enormously.
Commercial property can produce:
- Income
- Diversification
But leverage changes the risk.
A great building with dangerous debt can become a bad investment.
External Resource
For current commercial mortgage maturity and loan-performance research, review the Mortgage Bankers Association’s commercial and multifamily finance research:
https://www.mba.org/news-and-research/research-and-economics/commercial-multifamily-research
Continue Building Your Financial Knowledge
Read more practical investing, debt and wealth-building strategies on the True Wealth Moves blog:
https://truewealthmoves.com/wealth-blog
Use the True Wealth Moves resources page for financial tools, guides and calculators:
Final Verdict: Commercial Real Estate Refinancing 2026 Is About More Than Empty Offices
The most important word in commercial real estate refinancing 2026 is not:
real estate.
It is:
refinancing.
Many commercial properties survived the last few years because their old financing remained in place.
The true financial test arrives when that financing expires.
A building that could comfortably support:
3.5% debt
may struggle at:
6.5%.
A property once worth:
$40 million
may now be worth:
$28 million.
The new lender may refuse to replace the old loan completely.
That creates the refinancing gap.
But investors should avoid turning this into an exaggerated apocalypse story.
The approximately $5 trillion U.S. commercial mortgage market is diverse.
Some office properties are deeply stressed.
Other property categories remain healthy.
Commercial mortgage delinquencies across several lender groups actually improved during the second quarter of 2026.
Banks continue making new loans.
Commercial originations are recovering.
This means the next phase is likely to be about separation.
Strong properties refinance.
Weak properties restructure.
Some owners contribute new capital.
Some lenders take losses.
Some obsolete buildings change hands.
The risk becomes especially important when commercial-property problems begin affecting:
- Regional banks
- Small-business credit
- Local employment
- City tax revenue
- REIT investors
That is why ordinary people should understand the story.
Not because everyone needs to become a commercial real estate expert.
But because debt connects markets that appear unrelated.
An empty office tower can become a bank loss.
A bank loss can become tighter lending.
Tighter lending can affect a small business.
A small business can delay hiring.
That is how finance travels through the economy.
The True Wealth Moves conclusion is simple:
Commercial real estate does not become dangerous merely because buildings are empty. It becomes dangerous when the debt attached to those buildings can no longer be refinanced on terms the property can afford.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.