
Social Security COLA Planning: How to Budget When COLA Rises but Medicare + Housing Eat It Up
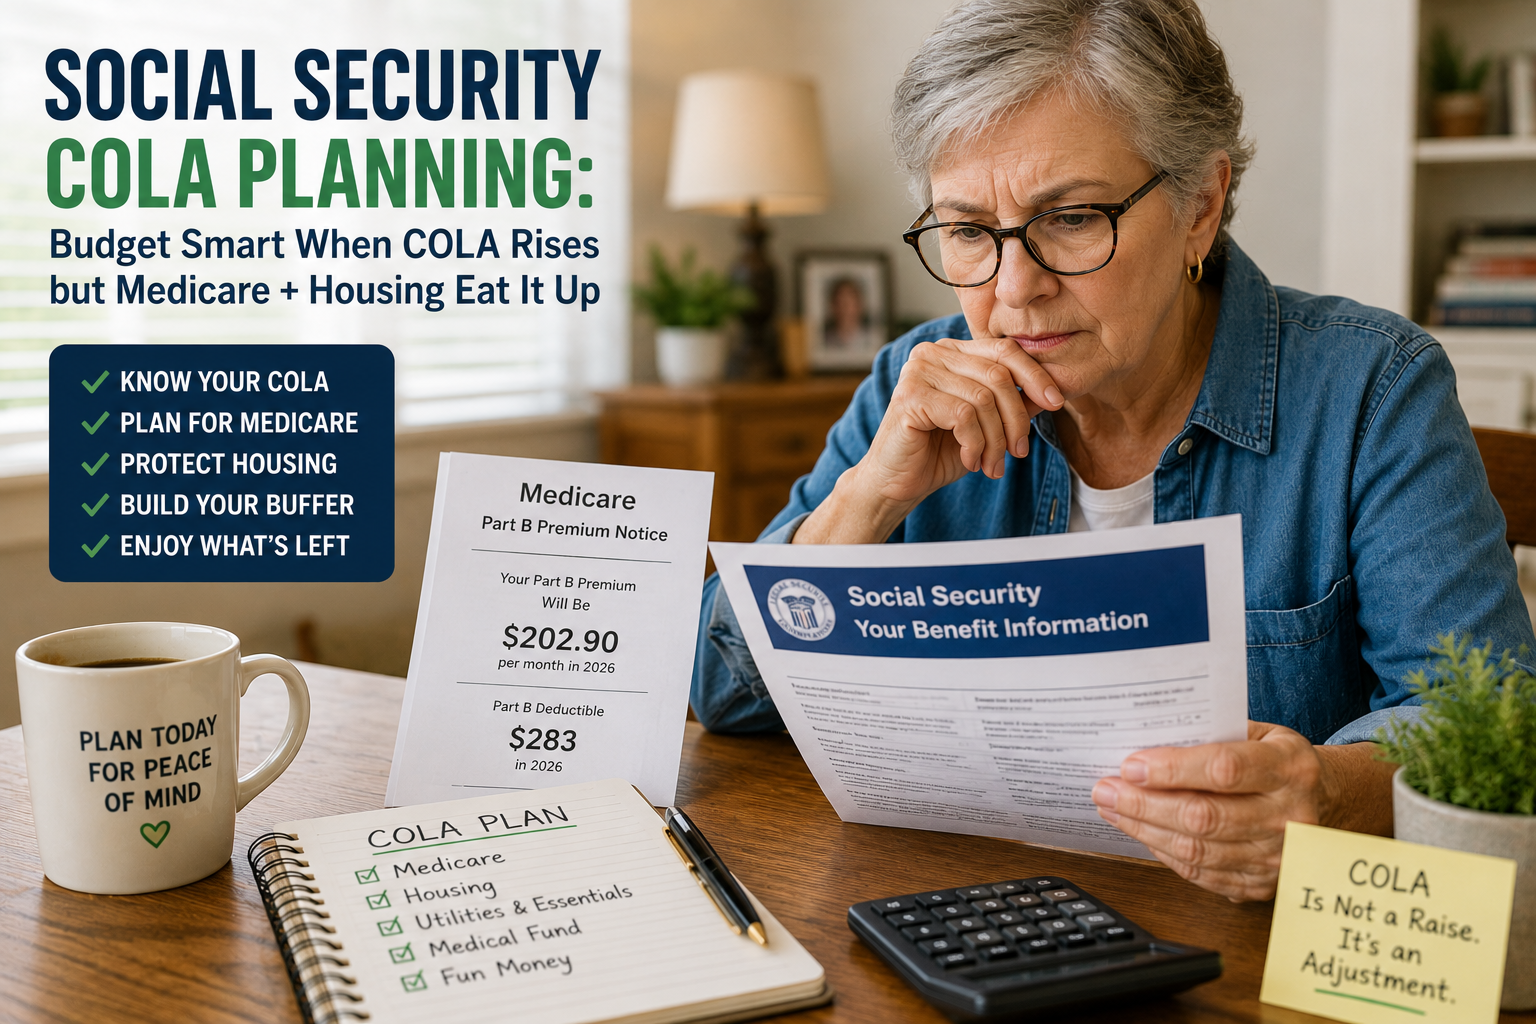
If you’re retired (or close to it), you’ve probably felt this weird emotional math:
You hear Social Security is getting a COLA increase…
But your bank account doesn’t feel richer.
It feels like the same struggle… just with higher price tags.
That’s why Social Security COLA planning matters.
Because COLA is designed to help benefits keep up with inflation — but in real life, many retirees see the increase get eaten up by Medicare premiums, rent or property taxes, utilities, and basic living costs.
So this post is a True Wealth Moves “retirement reality” guide:
- what COLA is and how it’s actually calculated
- why Social Security COLA planning is NOT the same thing as “getting a raise”
- what costs most commonly eat COLA (and why it feels unfair)
- the exact budget reset plan that protects your household
- and the simple system that keeps you stable even when costs rise faster than benefits
No politics.
No fear.
Just the plan that works.
What Social Security COLA planning really means
Social Security COLA planning is the strategy of budgeting and adjusting your retirement money around:
- your annual COLA increase (if any),
- your Medicare premiums and deductibles,
- your housing costs (rent, taxes, insurance),
- and your real-life inflation (which is often different from the headline number).
The goal is simple:
Use COLA intentionally so it strengthens your stability — instead of disappearing into higher bills.
How COLA is calculated (plain English)
The Social Security Administration (SSA) uses the CPI-W (Consumer Price Index for Urban Wage Earners and Clerical Workers) and compares the third quarter (July–September) average CPI-W to the third quarter of the previous year when a COLA was last determined. If there’s an increase, Social Security benefits and SSI can increase. If there’s no increase, there can be no COLA.
That matters because COLA is not “negotiated.”
It’s a formula.
Your evergreen, official reference link for this (use it whenever someone asks “where do they get COLA?”) is:
https://www.ssa.gov/cola/
Why Social Security COLA planning feels harder lately
Here’s the emotional truth:
Retirees don’t spend like the CPI basket.
Retirees spend more on:
- healthcare and prescriptions,
- housing and utilities,
- and basic necessities.
So even if the official inflation measure suggests a certain average, your personal inflation can feel higher — because the categories you buy most often are rising faster.
That’s why Social Security COLA planning needs to be personal, not generic.
The “COLA isn’t a raise” reality
Here’s the True Wealth Moves sentence to remember:
COLA is an inflation adjustment, not a lifestyle upgrade.
COLA is meant to preserve purchasing power — not expand it.
So if you treat a COLA increase like “extra spending money,” you can accidentally create stress:
- you raise your spending,
- then Medicare or rent rises,
- and suddenly you’re tight again.
Social Security COLA planning prevents that by forcing a smarter question:
“What costs will eat this COLA before I call it ‘extra’?”
The three costs that most often eat COLA
For most retirees, the “COLA eater” trio is:
1) Medicare premiums and deductibles
Medicare Part B has a standard monthly premium and a deductible that can rise year to year. For 2026, CMS reported the standard Part B premium is $202.90/month and the annual Part B deductible is $283.
Even if you’re not using many services, you still pay the premium.
So premium increases can swallow a big portion of a modest COLA.
2) Housing
Whether you rent or own, housing is usually the biggest line item:
- rent renewals,
- property taxes,
- HOA,
- homeowners insurance,
- or repairs.
If housing rises faster than COLA, your “increase” gets absorbed.
3) Utilities and essentials
Electricity, gas, water, groceries, and transportation costs can climb unevenly.
When energy and essentials spike, retirees feel it immediately because budgets are tighter and more predictable.
This is why Social Security COLA planning should assume:
COLA will be partially “pre-spent” by essentials.
The biggest mistake retirees make with COLA
The most common mistake is emotional:
COLA hits → “I can breathe” → spending rises → costs rise → stress returns.
This is not irresponsibility.
It’s human.
So the solution is a rule:
Don’t spend COLA until you run the COLA split.
The COLA split: a simple rule that keeps you safe
Here’s a safe default for Social Security COLA planning:
- 50% of COLA goes to “cost increases” (Medicare, housing, utilities, groceries)
- 30% goes to buffer/sinking funds (medical, home repairs, car repairs)
- 20% goes to quality-of-life (fun, travel, gifts) AFTER the first two are funded
Is that exact for everyone? No.
But it’s a powerful starting structure.
The point is: COLA gets assigned on purpose.
The Social Security COLA planning table
Social Security COLA planning table showing where COLA goes first, what tends to eat it, and how to assign the increase
| COLA category | What it covers | Why it eats COLA fast | Your move |
|---|---|---|---|
| Healthcare | Part B premium, deductible, copays, prescriptions | Costs can rise yearly and hit automatically | Fund a medical sinking fund first |
| Housing | Rent, taxes, insurance, HOA, repairs | Biggest fixed cost for most retirees | Lock a housing buffer and plan repairs |
| Utilities + essentials | power, water, groceries, transportation | Spikes are unpredictable | Build a price-shock mini fund |
| Quality of life | small joys, gifts, travel | Easy to overspend “because I earned it” | Spend only after essentials + buffer |
Screenshot this. This is the heart of Social Security COLA planning.
The retirement budget reset plan (step-by-step)
Now the practical system.
Step 1: Know your true monthly baseline
Write down your “non-negotiables”:
- housing
- Medicare premiums
- utilities
- groceries
- transportation
- minimum debt payments (if any)
- essential subscriptions (phone/internet)
This baseline is what COLA must protect first.
Step 2: Run the “COLA reality math”
When COLA hits, do this:
1) Estimate your monthly COLA increase.
2) Immediately subtract any known increases (Medicare Part B premium changes, rent renewal, insurance renewal).
3) What’s left is your “real COLA.”
This reduces emotional spending and forces reality.
Step 3: Build the Medical Sinking Fund (because Medicare is not the whole bill)
Even with Medicare, retirees still pay:
- deductibles,
- copays,
- prescriptions,
- dental/vision gaps,
- and surprise bills.
Your Social Security COLA planning needs a medical sinking fund because:
medical costs are the fastest way retirees end up using credit cards.
A simple target:
- Start with $500–$1,000 buffer
- Then aim for 1–2 months of typical medical spending (or your Part B deductible plus a cushion)
Step 4: Create a Housing Shock Fund
Housing is usually the biggest COLA eater.
If you rent:
- plan for renewal increases
- set aside a small “rent renewal cushion” monthly
If you own:
- plan for repairs (something always breaks)
- plan for taxes/insurance changes
Even $50–$100/month toward housing shocks can prevent panic.
Step 5: Use the “fixed-cost lockdown” on retirement spending
This is one of the best Social Security COLA planning moves:
Lower fixed costs so COLA goes further.
Target:
- phone plan
- internet plan
- subscriptions
- insurance policies (auto/home)
- unused memberships
Retirees often have “legacy subscriptions” they forgot about.
Cutting those makes COLA feel bigger without needing COLA to be bigger.
Step 6: Protect your cashflow with a bill schedule
This is a quiet retirement superpower:
List your bill due dates and align them with your Social Security payment schedule.
Keep a small checking buffer so autopays don’t bounce.
Bounced payments create fees and stress — and stress creates bad money decisions.
Step 7: The “No New Monthly Payments” rule
Retirees get trapped when they add payments:
- financing furniture,
- upgrading cars on payment,
- subscription stacking,
- carrying credit card balances.
In a Social Security COLA planning season, your rule is:
If it creates a new monthly payment, it needs a serious justification.
Because payments don’t care about COLA.
Step 8: If you’re working while on Social Security, plan around earnings limits
Some retirees work part-time.
That can be smart — but you must understand the earnings test if you’re under full retirement age.
SSA publishes the retirement earnings test limits each year.
This matters because you don’t want to accidentally lose benefits or create confusion.
If you work, plan your hours deliberately.
Step 9: Build the “Fun Budget” AFTER the buffers
This is how you enjoy life without fear.
Once healthcare and housing buffers are funded, then:
- plan gifts
- plan travel
- plan hobbies
COLA can support quality of life — but only after stability is protected.
That’s the difference between retired and relaxed vs retired and anxious.
How to budget when COLA rises but Medicare rises too
This is where most people need clarity.
If Medicare Part B rises and eats half your COLA:
Don’t pretend it didn’t happen.
Do this instead:
- Move a small amount of COLA into the medical fund automatically
- Reduce one fixed cost (subscription/phone/internet)
- Keep lifestyle spending flat for 60–90 days
- Then reassess
Your goal is not to “feel rich.”
Your goal is to remain stable.
The next 90 days after COLA hits: your stability routine
Here’s the routine that makes Social Security COLA planning work:
Weekly (10 minutes):
- check spending vs baseline
- confirm medical fund is building
- confirm grocery spending is controlled
Monthly (15 minutes):
- transfer to medical fund and housing shock fund
- review subscriptions
- adjust one category if needed
Quarterly (30 minutes):
- review insurance renewals
- review rent/property tax changes
- plan big expenses proactively
This routine beats stress.
One evergreen external link
Use this official SSA page as your one evergreen external link for this post:
https://www.ssa.gov/cola/
Two True Wealth Moves internal links (exactly two)
https://truewealthmoves.com/wealth-blog/
https://truewealthmoves.com/resources/
Final truth
COLA is helpful — but it’s not a raise.
Social Security COLA planning is how retirees stop the annual “hope and disappointment” cycle and start using COLA as a tool:
- protect healthcare
- protect housing
- build buffers
- reduce fixed costs
- then enjoy what’s left
That’s how you budget like a wealthy person on a fixed income — without fear.
Looking for More Finance Topics?
Use the search box below to explore hundreds of articles on True Wealth Moves — we’ve probably already written about what you’re looking for.





